ACG3341 Chapter 8 (Cost Accounting & Control 1)
Study these flashcardsFree · spaced repetition · iPhone, Android, Mac & web
All cards
1
What is
1) Job Costing
2) Process Costing
1) Job Costing
2) Process Costing
1) Job Costing: tracks costs for unique, custom projects or "jobs"
2) Process Costing: tracks costs for mass-produced, identical items
2) Process Costing: tracks costs for mass-produced, identical items
2
Fuly Explained
1) Actual costing
vs
2) Normal Costing
1) Actual costing
vs
2) Normal Costing
*PS: The only difference is how MOH is Calculated
1) Actual costing:
Step 1) During the Month, you record the Manufacturing Expenses
{Exmaples shown in image}
Step 2) Wait till the end of the period to put it into WIP Inventory
If, there is only one identical product, then just do
Dr Work-in-Progress Inventory 16,000
__Cr Manufacturing Overhead Control 16,000
HOWEVER, if there are multiple different types of items, then do
1st) You would have to wait to the end of the period to find "Total Actual indirect costs during that period / Total actual allocation base which happened that period" = Total Actual MOH cost rate (ex, 16,000 / 2,000 Machine hours = \$8.00 per machine hour)
2nd)
-Product A used 1,500 machine hours -> \$8 x 1,500 = \$12,000
-Product B used 500 machine hours -> \$8 x 500 = \$4,000
3rd) NOW, you can move it into WIP Inventory
Dr WIP (Product A) 12,000
Dr WIP (Product B) 4,000
__Cr Manufacturing Overhead Control 16,000
2) Normal Costing
Step 1) During the Period, you are constantly recording the ACTUAL Manufacturing Expenses
{Exmaples shown in image}
Step 2) During the Period, you are constantly recording the estimated Manfcauring Costs
-To do this, you need Budgeted MOH Rate = Total Budgeted MOH costs for the period / Total budgeted allocation base which is estimated to happen that period
2a) With Job Costsing, after a "job" is done, record this J/E
Dr WIP Inventory (\$# Budgeted MOH Rate x # of allocation base for that job)
_Cr Manufacuring Overhead Control (\$# Budgeted MOH Rate x # of allocation base for that job)
2b) With process Costing, every day (would be another period but this is what's most common) you just record the amount of allocation base which happened and multiply it by the Budgetd MOH Rate
Dr WIP Inventory (\$# Budgeted MOH Rate x # of allocation base for that day)
__Cr Manufacturing Overhead Control (\$# Budgeted MOH Rate x # of allocation base for that day)
Step 3) At the end of the period, you could have over or under estimated, so you need to make ADJUSTMENTS! to make the MOH Control account = \$0!!
3a) If you underestimated (underapplied) ( Left Side > Right Side) (Debits > Credits)(Actual > Estimated)
(ex, you underestimated by 1,000)
Direct Write Off Method
Dr COGS 1,000
__Cr MOH Control 1,000
Prorated Method
Dr WIP Inventory (20% of COGS + FCG+ WIP) 200
Dr FG Inventory (30% of COGS + FCG+ WIP) 300
Dr COGS (50% of COGS + FCG+ WIP) 500
__Cr MOH Control 1,000
3b) If you overestimated (overapplied) ( Left Side < Right Side) (Debits < Credits)(Actual < Estimated)
(ex, you overestimated by 1,000)
Direct Write Off Method
Dr MOH Control 1,000
__Cr COGS 1,000
Prorated Method
Dr MOH Control 1,000
__Cr WIP Inventory (20% of COGS + FCG+ WIP) 200
__Cr FG Inventory (30% of COGS + FCG+ WIP) 300
__Cr COGS (50% of COGS + FCG+ WIP) 500
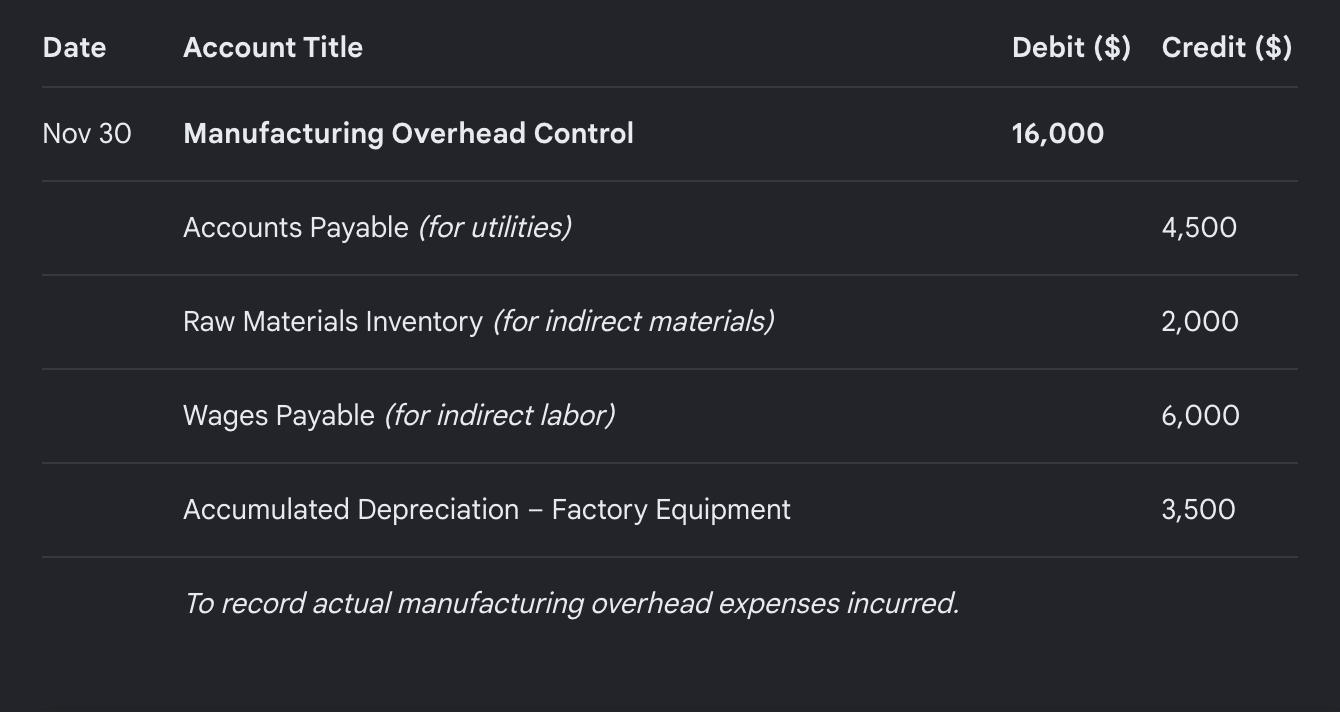
1) Actual costing:
Step 1) During the Month, you record the Manufacturing Expenses
{Exmaples shown in image}
Step 2) Wait till the end of the period to put it into WIP Inventory
If, there is only one identical product, then just do
Dr Work-in-Progress Inventory 16,000
__Cr Manufacturing Overhead Control 16,000
HOWEVER, if there are multiple different types of items, then do
1st) You would have to wait to the end of the period to find "Total Actual indirect costs during that period / Total actual allocation base which happened that period" = Total Actual MOH cost rate (ex, 16,000 / 2,000 Machine hours = \$8.00 per machine hour)
2nd)
-Product A used 1,500 machine hours -> \$8 x 1,500 = \$12,000
-Product B used 500 machine hours -> \$8 x 500 = \$4,000
3rd) NOW, you can move it into WIP Inventory
Dr WIP (Product A) 12,000
Dr WIP (Product B) 4,000
__Cr Manufacturing Overhead Control 16,000
2) Normal Costing
Step 1) During the Period, you are constantly recording the ACTUAL Manufacturing Expenses
{Exmaples shown in image}
Step 2) During the Period, you are constantly recording the estimated Manfcauring Costs
-To do this, you need Budgeted MOH Rate = Total Budgeted MOH costs for the period / Total budgeted allocation base which is estimated to happen that period
2a) With Job Costsing, after a "job" is done, record this J/E
Dr WIP Inventory (\$# Budgeted MOH Rate x # of allocation base for that job)
_Cr Manufacuring Overhead Control (\$# Budgeted MOH Rate x # of allocation base for that job)
2b) With process Costing, every day (would be another period but this is what's most common) you just record the amount of allocation base which happened and multiply it by the Budgetd MOH Rate
Dr WIP Inventory (\$# Budgeted MOH Rate x # of allocation base for that day)
__Cr Manufacturing Overhead Control (\$# Budgeted MOH Rate x # of allocation base for that day)
Step 3) At the end of the period, you could have over or under estimated, so you need to make ADJUSTMENTS! to make the MOH Control account = \$0!!
3a) If you underestimated (underapplied) ( Left Side > Right Side) (Debits > Credits)(Actual > Estimated)
(ex, you underestimated by 1,000)
Direct Write Off Method
Dr COGS 1,000
__Cr MOH Control 1,000
Prorated Method
Dr WIP Inventory (20% of COGS + FCG+ WIP) 200
Dr FG Inventory (30% of COGS + FCG+ WIP) 300
Dr COGS (50% of COGS + FCG+ WIP) 500
__Cr MOH Control 1,000
3b) If you overestimated (overapplied) ( Left Side < Right Side) (Debits < Credits)(Actual < Estimated)
(ex, you overestimated by 1,000)
Direct Write Off Method
Dr MOH Control 1,000
__Cr COGS 1,000
Prorated Method
Dr MOH Control 1,000
__Cr WIP Inventory (20% of COGS + FCG+ WIP) 200
__Cr FG Inventory (30% of COGS + FCG+ WIP) 300
__Cr COGS (50% of COGS + FCG+ WIP) 500
3
"Actual MOH" vs "Applied MOH"?
Actual MOH: The real exact Expense
Applied MOH: The estimated MOH expense
(Actual Costsing does NOT have Applied MOH)
Applied MOH: The estimated MOH expense
(Actual Costsing does NOT have Applied MOH)
4
1) What is a Clearing Account?
2) Would MOH Control Account be considered a Clearing Account?
2) Would MOH Control Account be considered a Clearing Account?
"A clearing account is a temporary general ledger account used to hold financial transactions for a short time before they are moved to their final destination accounts."
2) YES!
2) YES!
5
In Normal Costing, what is the Debit vs Credit of the MOH Contorl Account?
Debit: Actual MOH
Credit Applied (estimated) MOH
*Image only for extra context, though don't worry too much about it.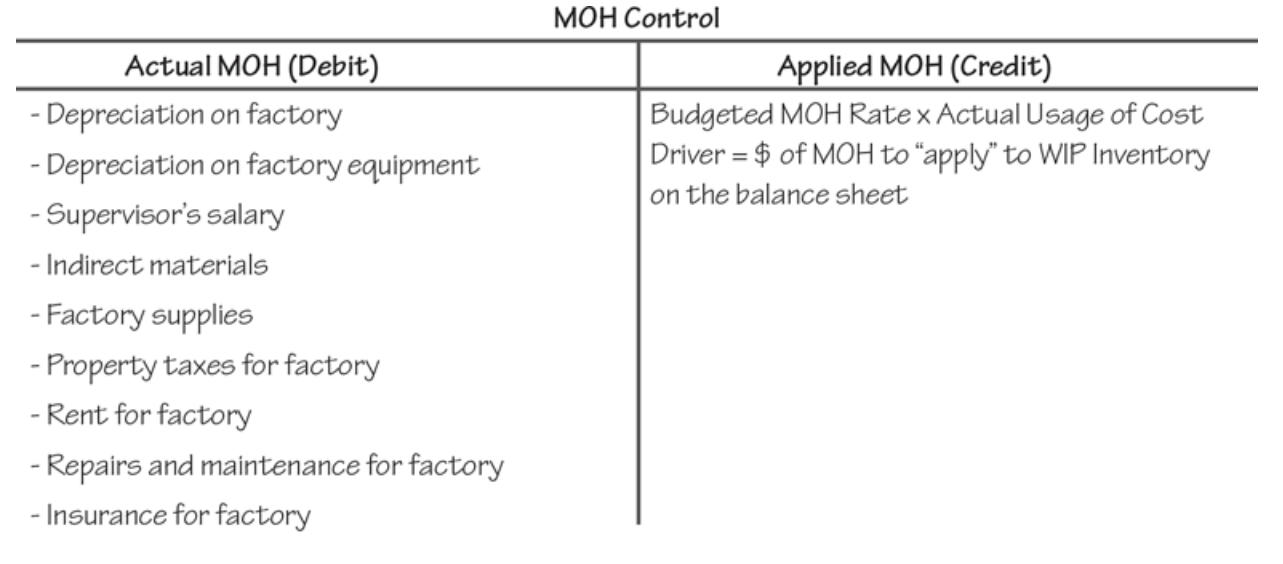
Credit Applied (estimated) MOH
*Image only for extra context, though don't worry too much about it.
6
Another term for budgeted MOH rate is
Predetermined MOH Rate
7
Another term for allocation base is
Cost Drivers
8
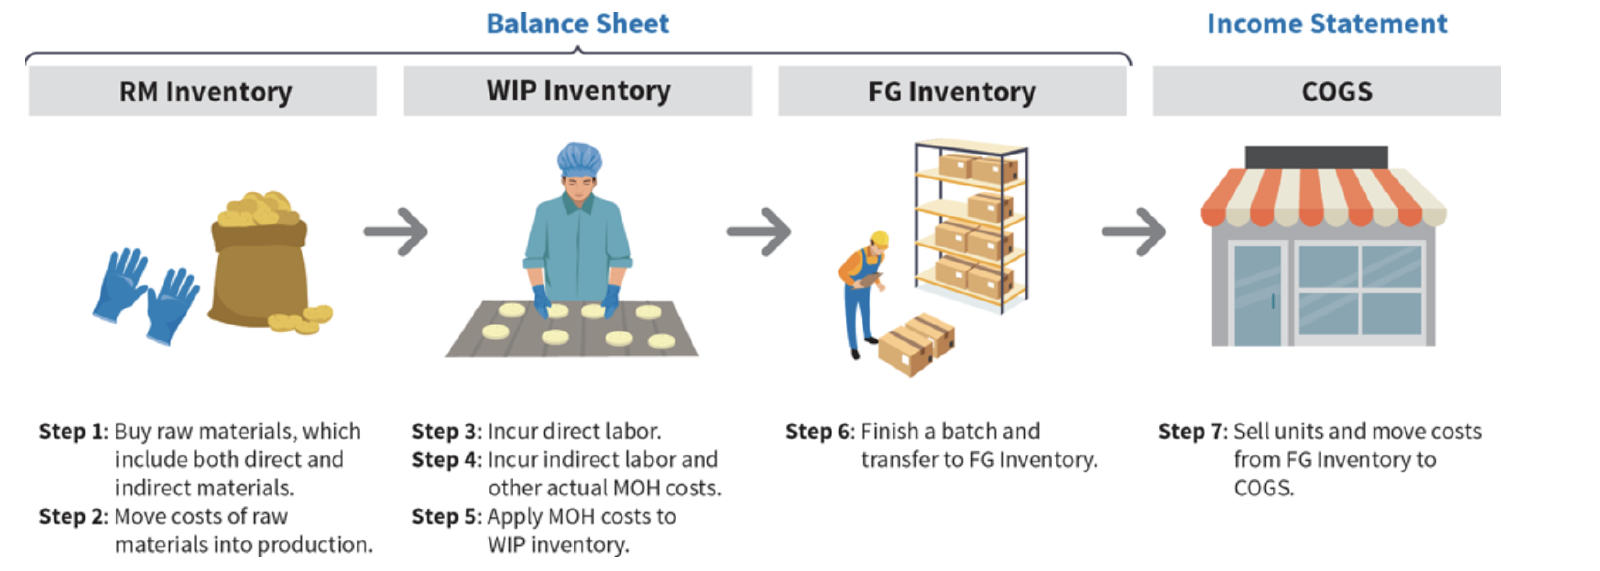
Flow of job costs from the balance sheet to the income statement (Include all J/E)
Step 1) Buy Raw Materials (direct & Indirect)
Dr Raw Materials Inventory
__Cr Cash / Accounts Payable
Step 2) Move Raw Materials into production
Dr WIP Inventory (for direct materials)
Dr Manufacturing Overhead Control (for indirect materials)
__Cr Raw Materials Inventory (total)
Step 3) Incur Direct Labor
Dr WIP Inventory
__Cr Wages Payable
Step 4) Incur ACTUAL MOH costs
Dr Manufacturing Overhead Control
__Cr Wages Payable (Indirect Labour) / Raw Materials (Indirect Materials) / Utilities Payable / Accumulated Depreciation / Cash
Step 5) Apply MOH to WIP
Dr WIP
__Cr Manufacturing Overhead Control
*(Look at the 2nd Flash Card to see all the details on all the ways this can be calculated)
Step 6) Finish batch and transfer to FG Inventory
Dr FG Inventory
__Cr WIP Inventory
Step 7) Sell units
Dr Cash / Accounts Receivable
__Cr Sales Revenue
Dr COGS
__Cr FG Inventory
*(Step 8 I added, You would need adjustments if you over or under applied MOH using the normal costing method?)
Dr Raw Materials Inventory
__Cr Cash / Accounts Payable
Step 2) Move Raw Materials into production
Dr WIP Inventory (for direct materials)
Dr Manufacturing Overhead Control (for indirect materials)
__Cr Raw Materials Inventory (total)
Step 3) Incur Direct Labor
Dr WIP Inventory
__Cr Wages Payable
Step 4) Incur ACTUAL MOH costs
Dr Manufacturing Overhead Control
__Cr Wages Payable (Indirect Labour) / Raw Materials (Indirect Materials) / Utilities Payable / Accumulated Depreciation / Cash
Step 5) Apply MOH to WIP
Dr WIP
__Cr Manufacturing Overhead Control
*(Look at the 2nd Flash Card to see all the details on all the ways this can be calculated)
Step 6) Finish batch and transfer to FG Inventory
Dr FG Inventory
__Cr WIP Inventory
Step 7) Sell units
Dr Cash / Accounts Receivable
__Cr Sales Revenue
Dr COGS
__Cr FG Inventory
*(Step 8 I added, You would need adjustments if you over or under applied MOH using the normal costing method?)
9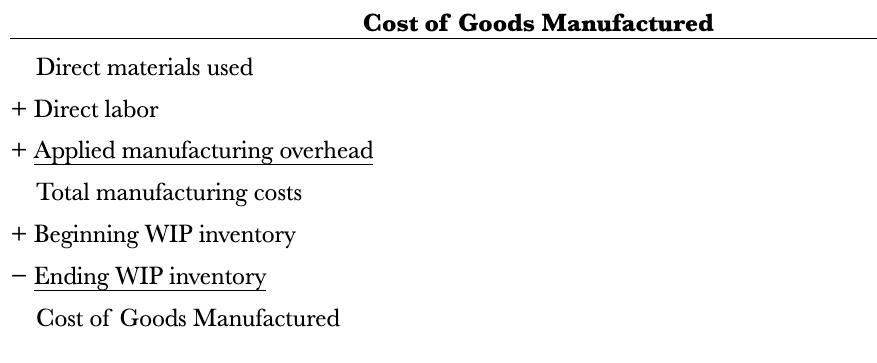
Cost of Goods Manufactured
10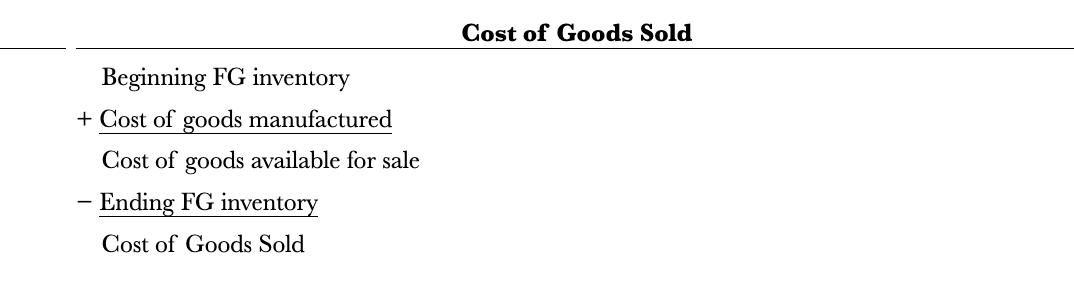
Cost of Goods Sold
11
Is Freight In included into RM Invnetory Costs?
YES!
12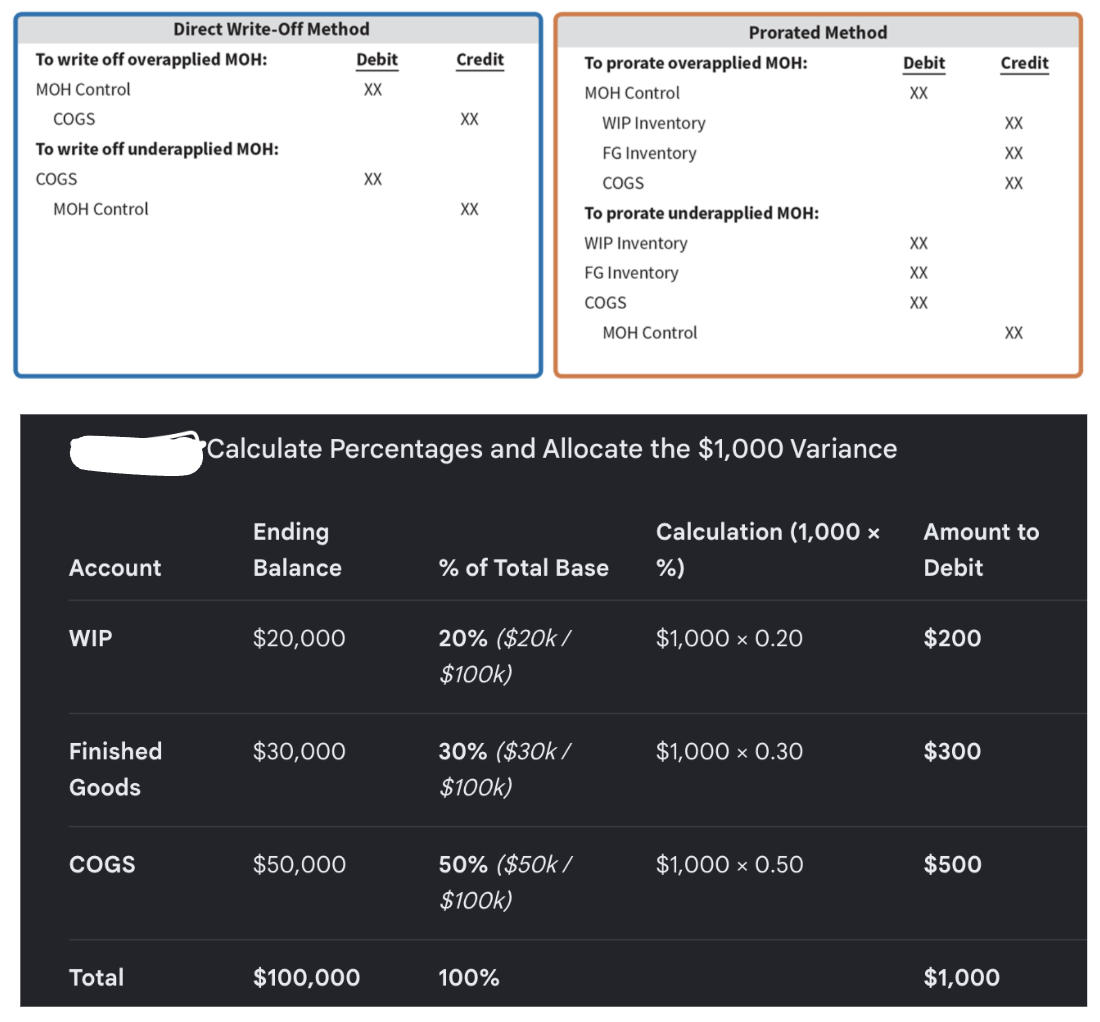
When doing normal costing method, how to adjust at the end? (What are the two methds)
13
Bills of Material
"The list of materials (and required quantities) needed to manufacture the product."
14
Materials requisition sheet.
"The formal request to remove specific items from the raw material storage area to begin a production run."
15
Labor Time Sheet
"The document that records the workers scheduled on today’s production run, which job number they’re working on, and how long they work on each job."
16
Job cost sheet.
"The control document which compiles the quantities and costs used for DM, DL, and applied MOH for each job. The job cost sheet will be identified by a specific job number."
17
In Normal Costing, when cosntiisly applying estimated MOH to WIP Inventory, what is Budgeted vs Actual Cost Driver (ex, direct labour hours) used for.
Step 1) Find the Budgetd MOH Rate (Budgeted MOH Rate = Total Budgeted MOH costs for the period / Total budgeted allocation base which is estimated to happen that period)
Step 2) Multiply the Budgeted MOH rate by the ACTUAL Cost driver which ACTUALLY HAPPENED!!!!!!!
Step 2) Multiply the Budgeted MOH rate by the ACTUAL Cost driver which ACTUALLY HAPPENED!!!!!!!
18
MOH Control normal balance?
Debit
19
debit to Manufacturing Overhead Control and a credit to Accumulated Depreciation-Factory.
The journal entry to record actual depreciation on factory is a
debit to Manufacturing Overhead Control and a credit to Accumulated Depreciation-Factory.
More Business & economics flashcards
Fx Transactions HedgingBusiness & economics · EnglishTiredofBus2000Memory ManagementBusiness & economics · English—Griffith—ATI Leadership Final Learning SystemsBusiness & economics · EnglishCatSampling Paving Mix and StockpilesBusiness & economics · Englishae20202024Accounting: Depreciation and Asset RetirementBusiness & economics · EnglishColeFinance: Financial MarketsBusiness & economics · EnglishMauMarketing (Bus 2000)Business & economics · EnglishTiredofBus2000ACG 3103 Chapter 7 (Intermediate Financial Accounting)Business & economics · EnglishAndrewEcon 101 All TermsBusiness & economics · EnglishVincentIntroduction to MarketingBusiness & economics · Englishrikishakennedyeconomics unit 2 testBusiness & economics · EnglishLizetteMan Acc ExamBusiness & economicsLexie
All Business & economics decks
Study these decks in the app
Free on iPhone, Android, Mac and the web. Add any deck to your account in one tap.

