Variances
Study these flashcardsFree · spaced repetition · iPhone, Android, Mac & web
All cards
1
What are planning variances
A planning variance measures the difference between the budgeted and actual
profit that has been caused by external changes in the original standard cost
that may not have been known or acknowledged by standard-setters at the time
of planning. It is the difference between the original (ex ante) and the revised
(ex post) standards.
profit that has been caused by external changes in the original standard cost
that may not have been known or acknowledged by standard-setters at the time
of planning. It is the difference between the original (ex ante) and the revised
(ex post) standards.
2
what is responsibility accounting
In reporting variances, the concept of responsibility accounting should
be followed so that a variance report to an individual manager should
only include figures relating to their own area of responsibility i.e. within
their area of control.
For example, regional sales managers might be sent variance reports
showing sales price and sales volume variances for their region.
Production managers might be sent variance reports relating to
materials usage, labour efficiency and other items of expenditure under
their control. Similarly, detailed reports on overhead expenditure
variances might be sent to the managers responsible for departmental
spending
3
What are operational variances
Operational variances are variances that are assumed to have occurred due to
operational factors. They are calculated by comparing the actual results with the
‘realistic’ revised standard. They are calculated in exactly the same way as
described in earlier chapters, the only difference being that the actual results
are compared with the revised standard, not the original standard.
• The operational variance is controllable by operational managers and, as
such, they should be held accountable for the variance
4
How is sales price variance calculated
by comparing the actul price recieved with the original price budgeted and multiplying the difference by the actual quantity sold
5
How is the sales quantity profit variance calculated
Actual sales quantity less budgeted sales quantity times weighted average contribution
6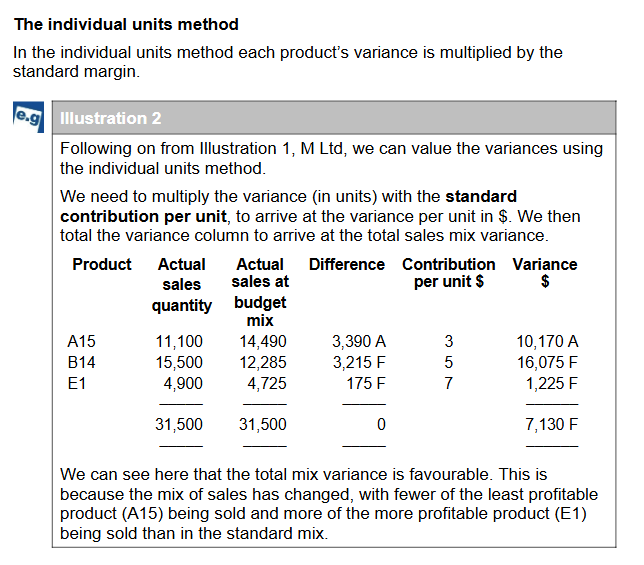
Sales mix individual method
7
Sales mix weighted average
The weighted average method for the mix variance is viewed as being superior to the individual units method. it is easier to see the impact of each individual product or service when it is measured against the average margin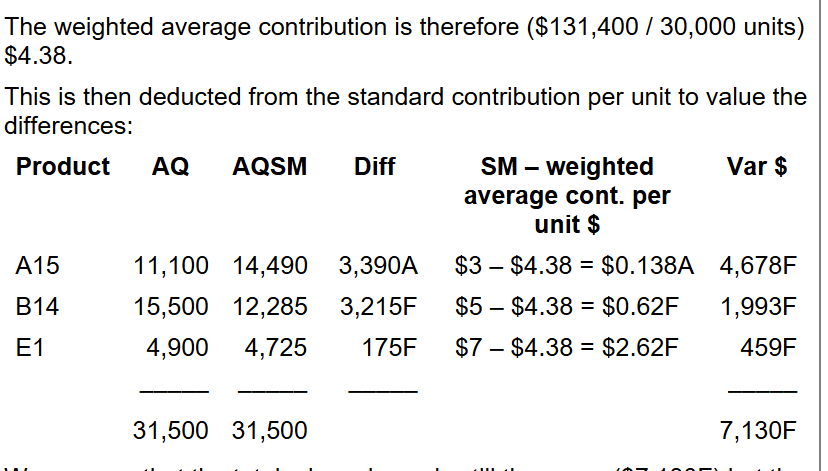
8
Sales quantity variance for sales mix
same as sales quantity profit variance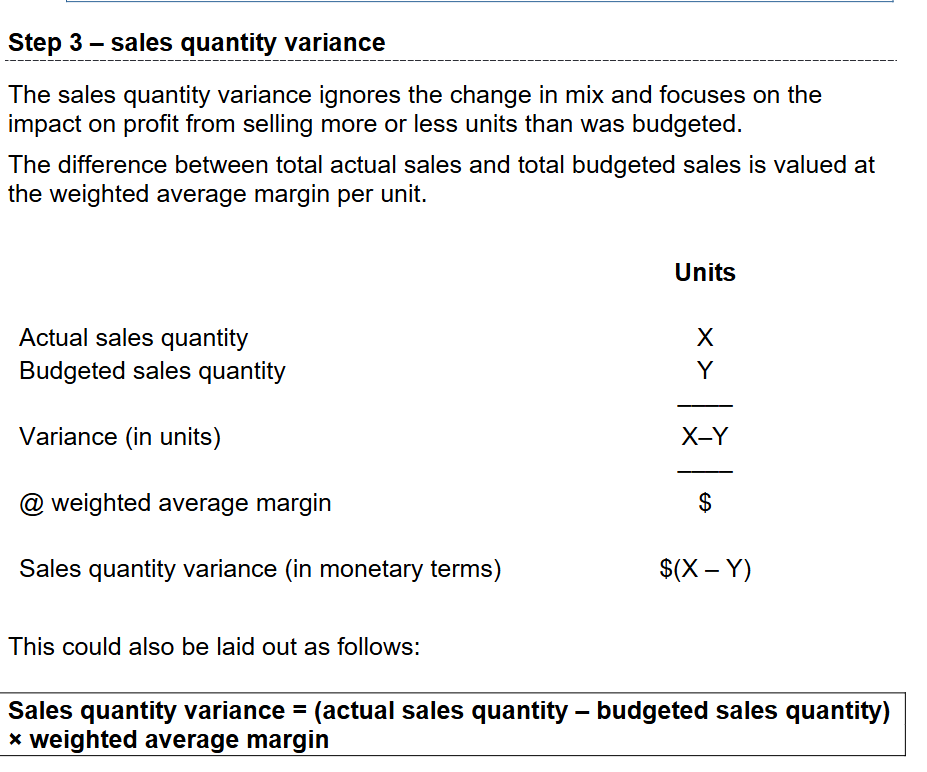
9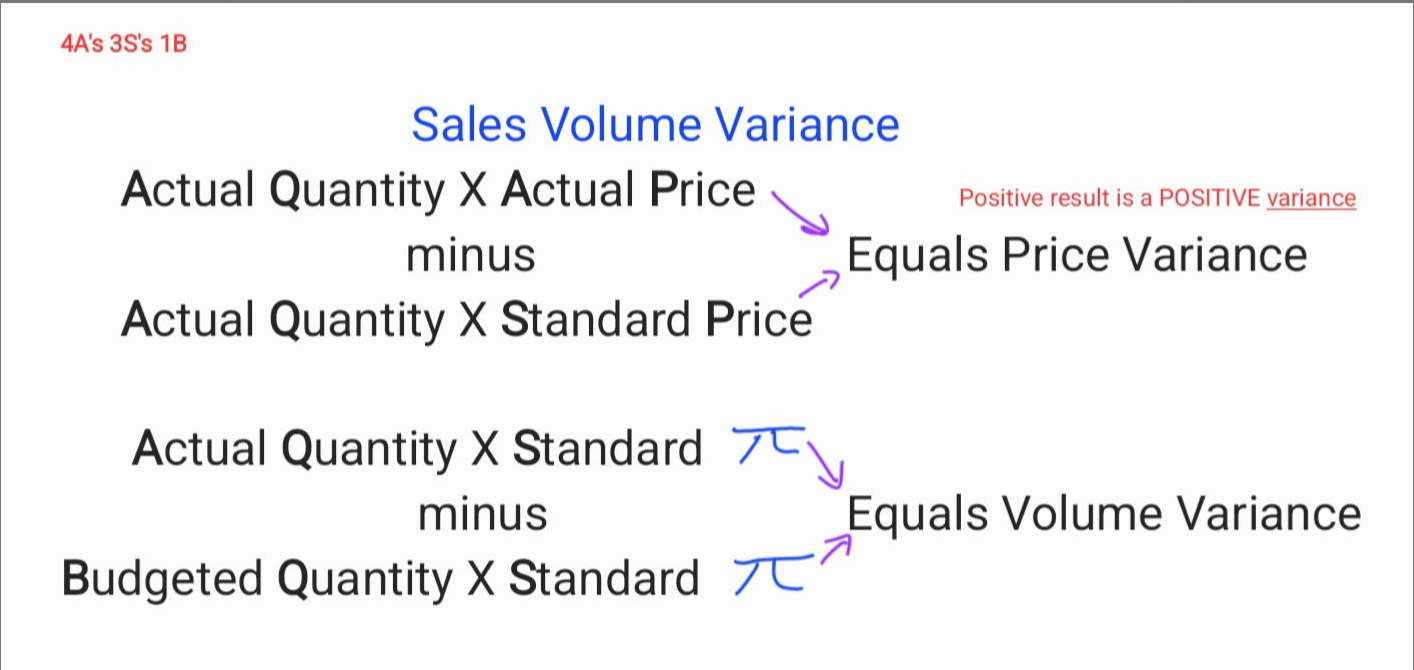
Sales price and volume variance
10
which 2 sales variances equal the sales volume variance
sales mix and sales quantity
11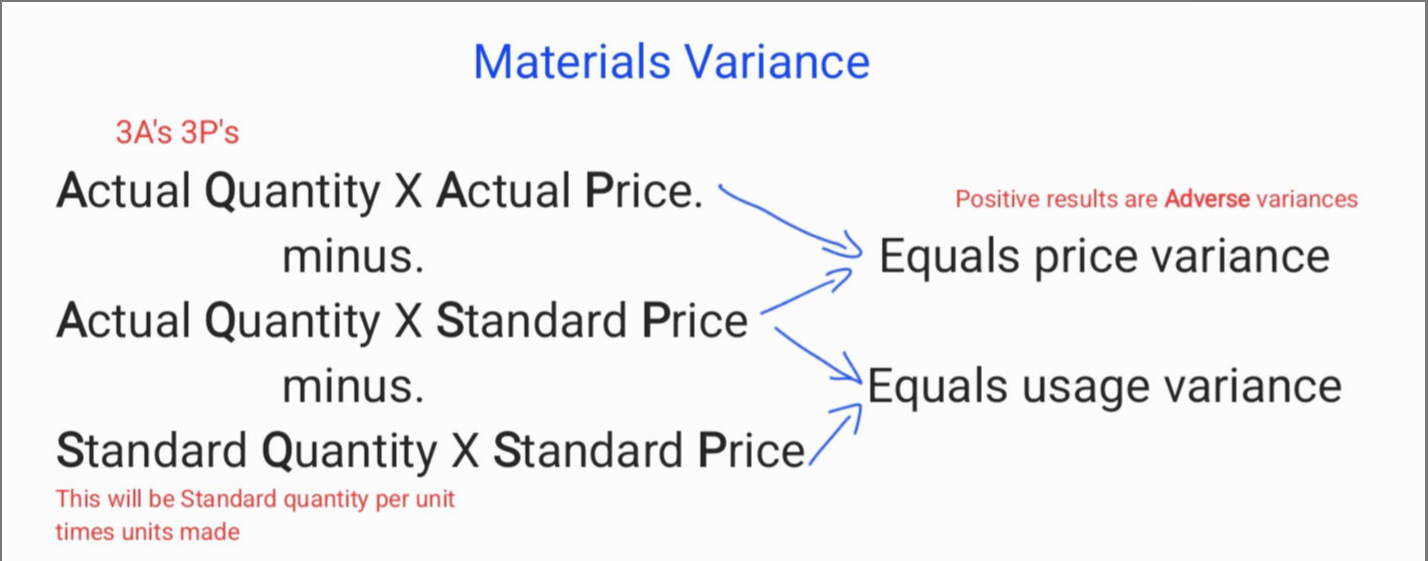
Materials variance
12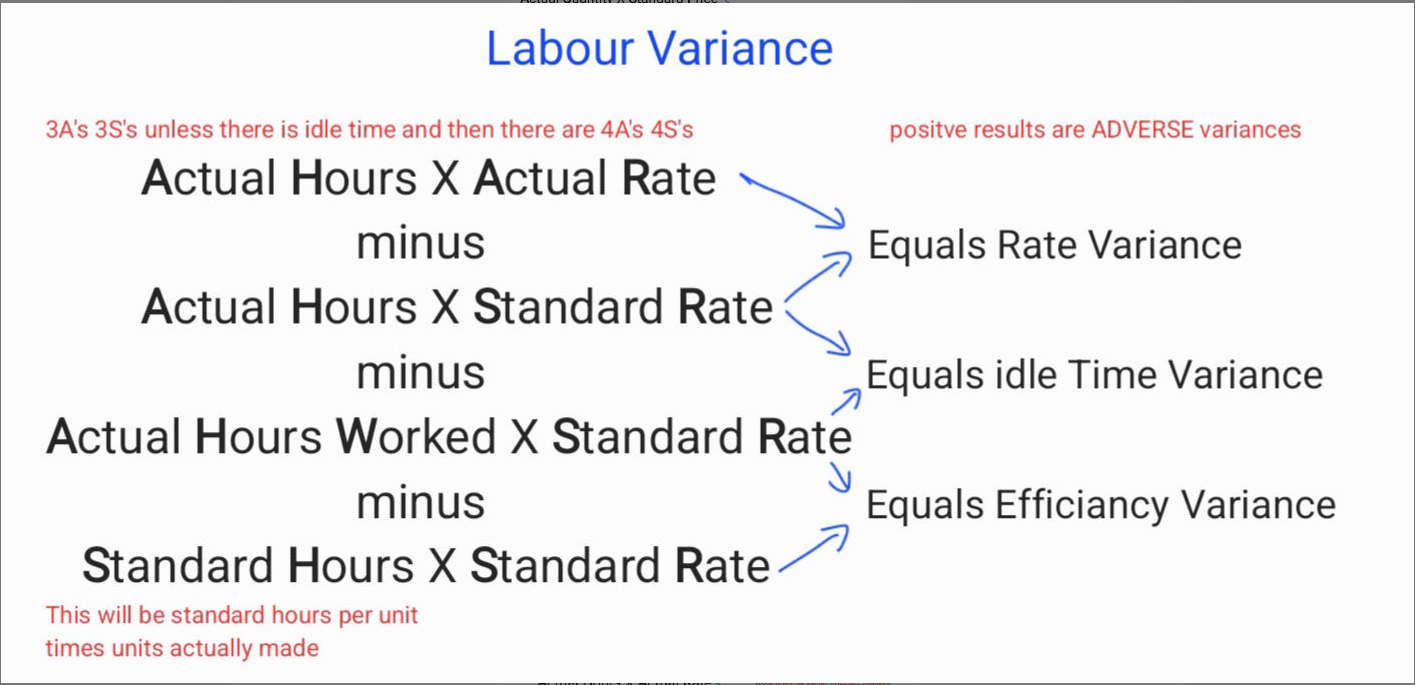
Labour variance
13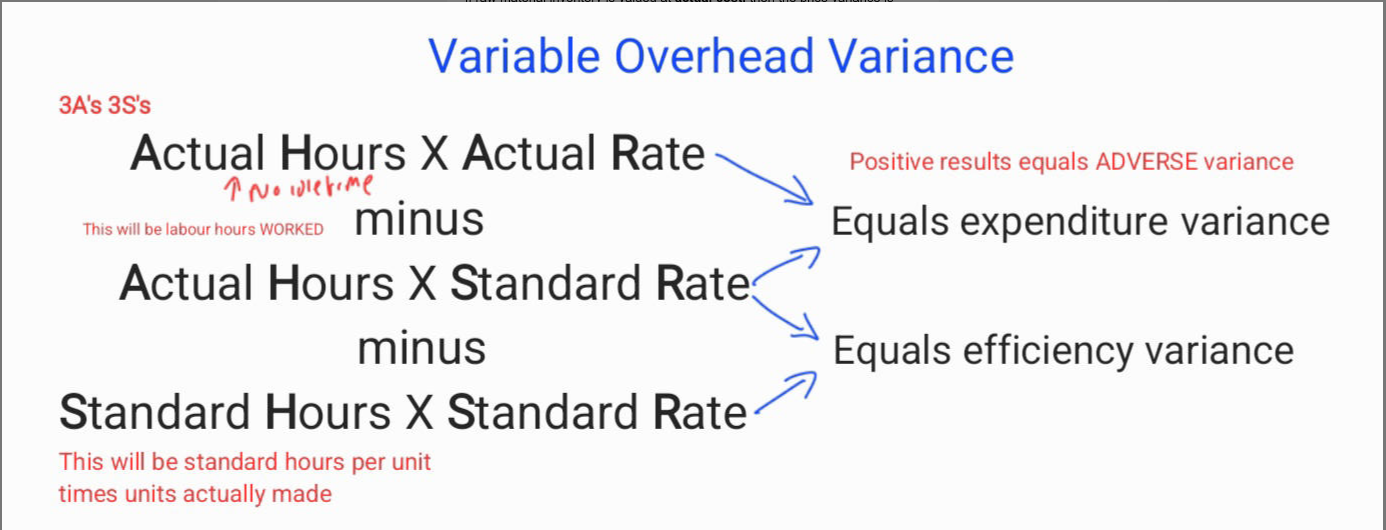
Variable overhead variance
14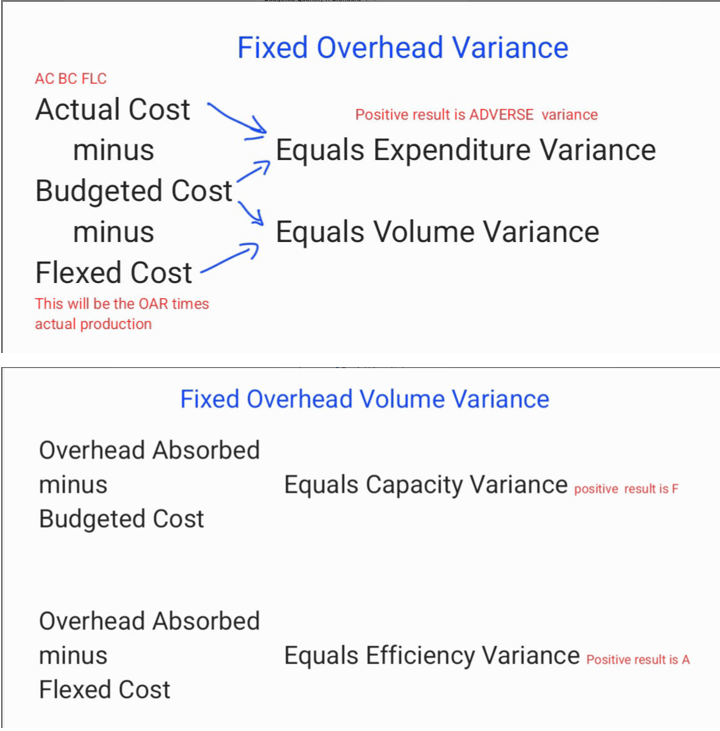
Fixed overhead variance
15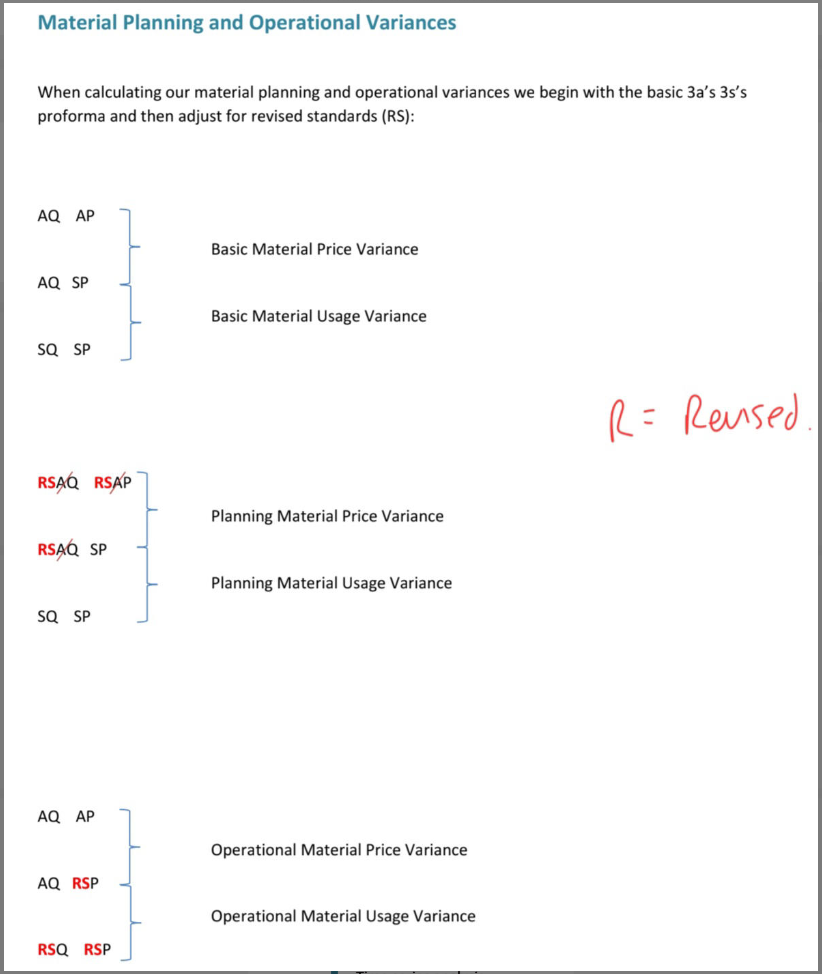
Material planning & operational variances
16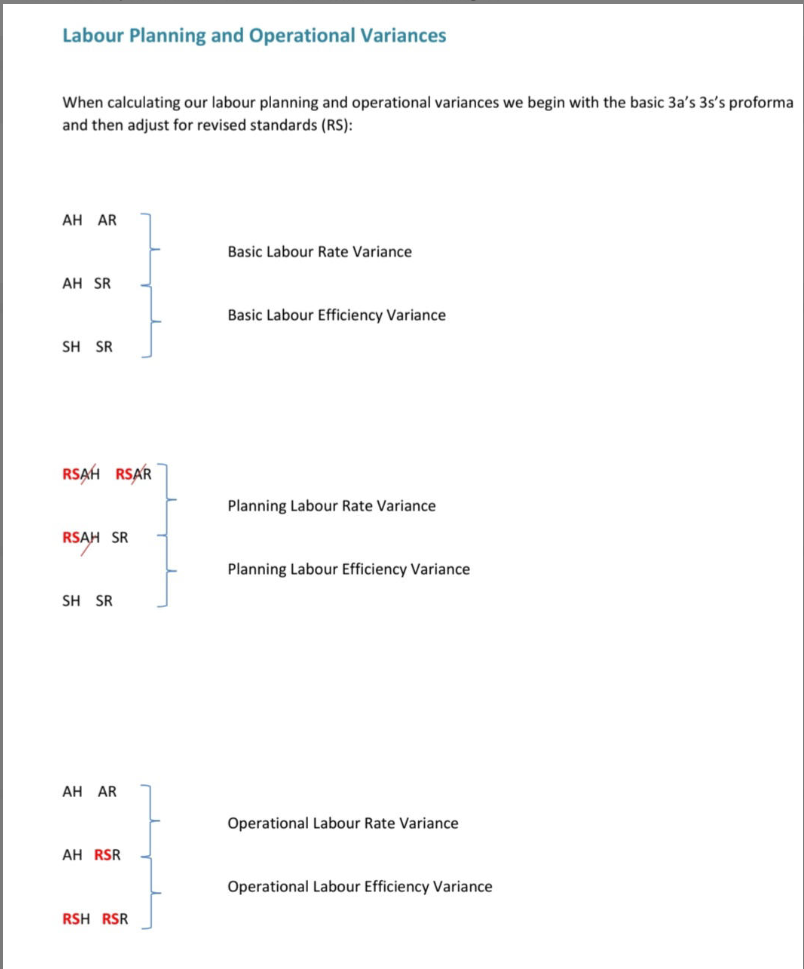
Labour planning & operational variances