F2 The Consolidated SOCIE
Study these flashcardsFree · spaced repetition · iPhone, Android, Mac & web
All cards
1
In the consolidated statement of changes in equity, whose share capital and share premium are included?
Only the parent’s share capital and share premium are included.
2
How are dividends treated in the consolidated statement of changes in equity for the parent and NCI?
The parent’s dividend is shown in the column for equity attributable to the parent. The NCI column shows only the NCI’s share of the subsidiary’s dividend.
3
Why is only the NCI’s share of the subsidiary’s dividend shown in the NCI column?
Because the parent’s share of the subsidiary’s dividend is eliminated (cancelled with investment income) in consolidation.
4
In the example, if the parent owns 90% of the subsidiary and the subsidiary pays a dividend of 20,000, how much is shown in the NCI column?
10% of 20,000 = 2,000 is shown in the NCI column.
5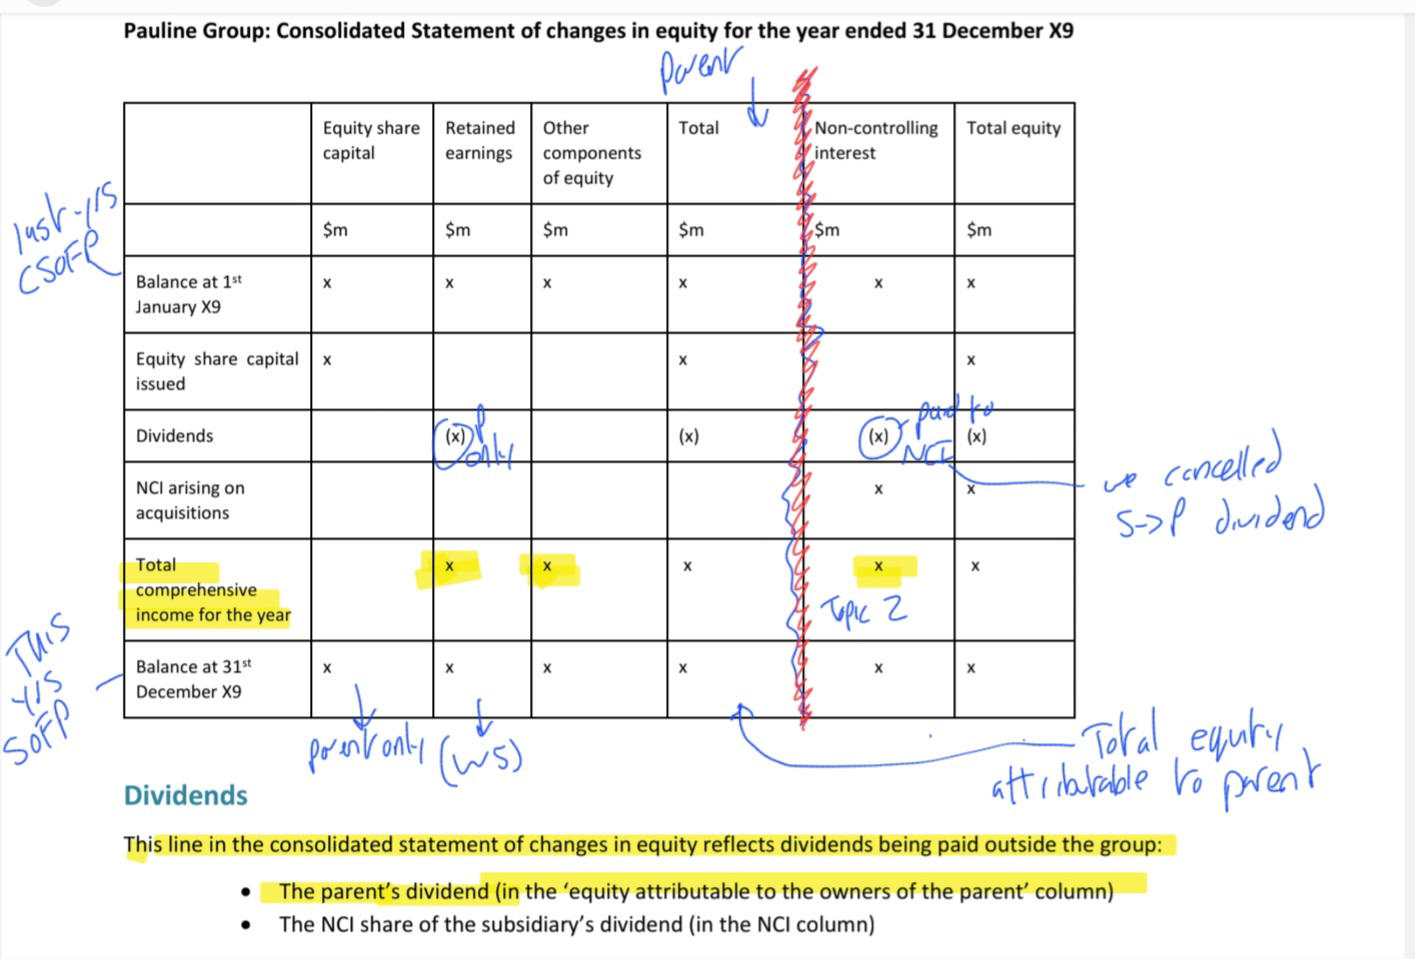
What is the proforma for group statement of changes in equity?
6
What is included in a statement of changes in equity
Equity BF
Comprehensive income
Dividends
Equity carried forward
Comprehensive income
Dividends
Equity carried forward
7
What is improtant to remember when doing a consolidated statement of changes in equity (CSOCIE)
You are doing the same thing as with the other statements, parents figures include their proportion of the subs figures. You have to do the same eliminations (ie dividends paid to parent)
NCI is also the same, its the proportion of the individual figures not attributable to the parent
NCI share capital & share premium will not be included
NCI is also the same, its the proportion of the individual figures not attributable to the parent
NCI share capital & share premium will not be included
8
What is equity equal to?
Net assets
9
How do you calculate the attributable to parent B/F equity
100% parent B/f equity
plus parents % of post aquisition B/f of Sub ( you will need to deduct the subs equity at aquisition from the subs bf equity) before apportioning
plus parents % of post aquisition B/f of Sub ( you will need to deduct the subs equity at aquisition from the subs bf equity) before apportioning
10
How do you calculate the NCI b/f equity
Value of NCI at aquisition
plus NCI % of post aquisition profit up to B/F date (you will need to deduct their equity at aquisition from the B/F balance on their statement before multiplying by their %)
plus NCI % of post aquisition profit up to B/F date (you will need to deduct their equity at aquisition from the B/F balance on their statement before multiplying by their %)
11
How do you calculate the equity C/F attributable to parent
100% parent equity C/F
plus parents % of (sub C/F equity minus sub equity at aquisition)
plus parents % of (sub C/F equity minus sub equity at aquisition)
12
How do you calculate NCI equity C/F
NCI at aquisition
plus NCI proportion of (NCI equity C/F minus NCI equity at aquisition)
plus NCI proportion of (NCI equity C/F minus NCI equity at aquisition)
13
How do you calculate the comprehensive income attributable to parent
100% parent comprehensive income
PLUS parent % of Subs comprehenssive income
LESS dividends paid from sub to parent
PLUS parent % of Subs comprehenssive income
LESS dividends paid from sub to parent
14
How do you calculate subs comprehensive income
NCI % of comprehensive income
15
How do you calculate NCI dividends paid
Subs divident paid
LESS divident paid to parent
LESS divident paid to parent
16
How do you calcualte parent dividends paid
100% parents dividend paid