F2 Foreign Currency Translation
Study these flashcardsFree · spaced repetition · iPhone, Android, Mac & web
All cards
1
What is a functional currency?
The currency that dominates the primary economic environment in which the subsidiary operates; it is not a choice but determined by economic factors.
2
What factors help determine a subsidiary’s functional currency?
actors include the currency influencing sales prices, competitive forces, currency for labor/materials, funding sources, and where profits are retained.
3
Summarise the method for doing a consolidated SOFP with foreign subsidiary
4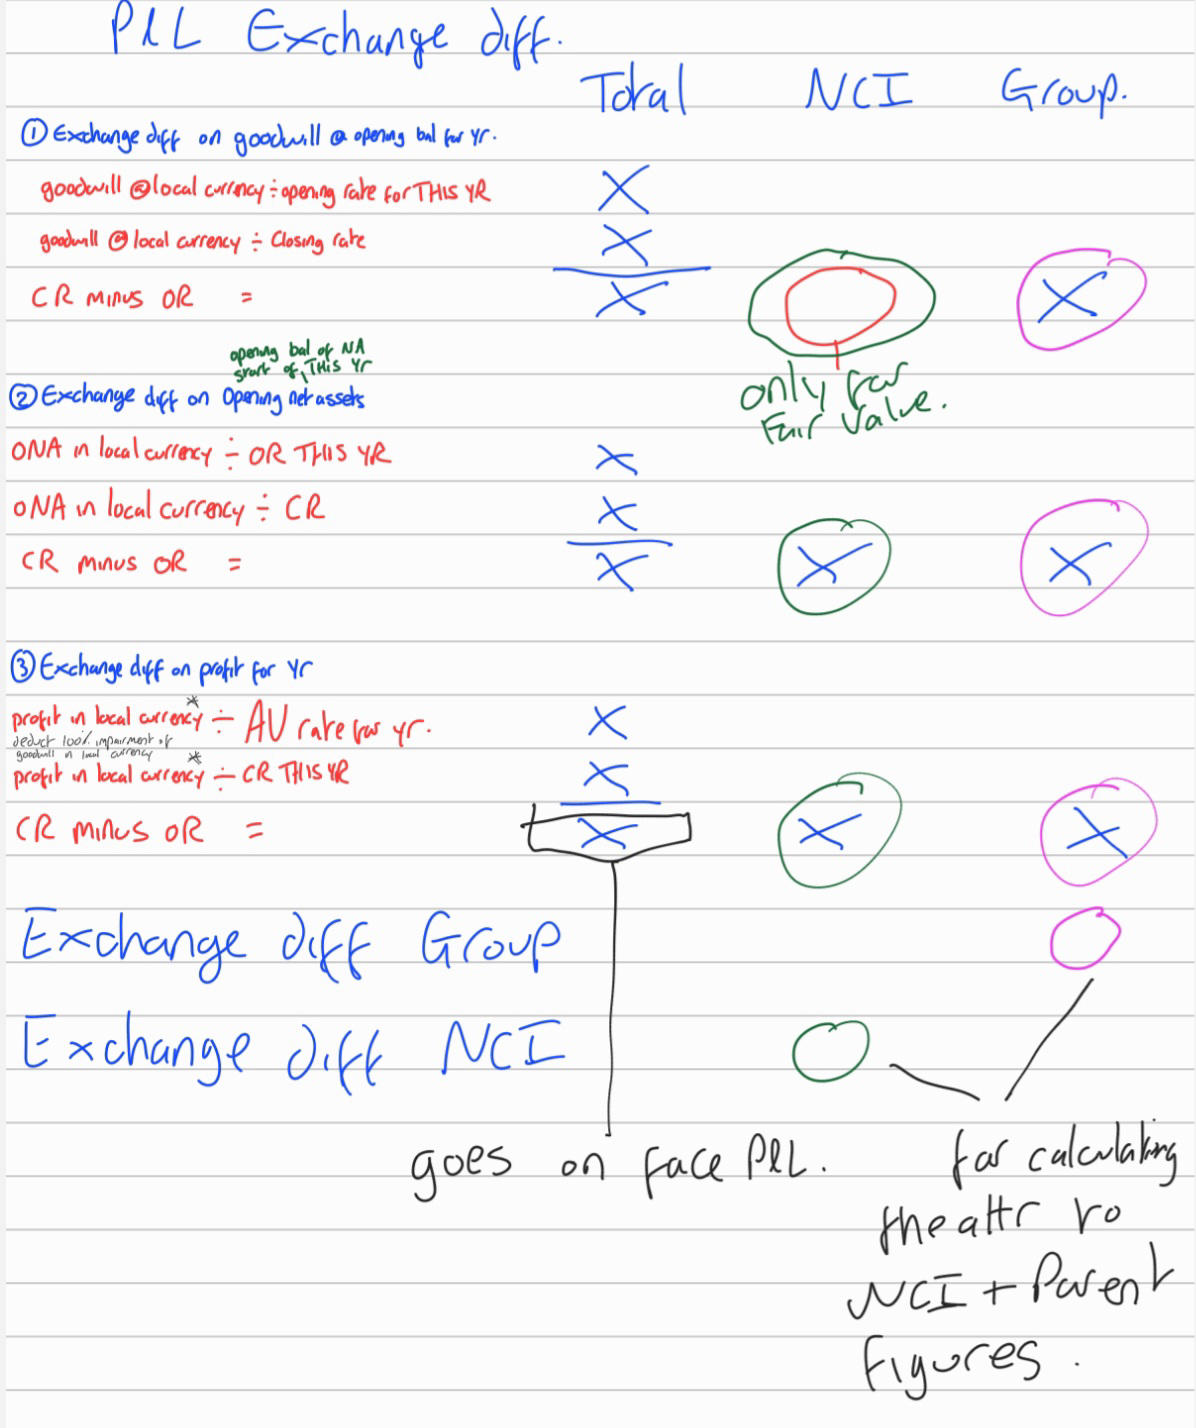
Summarise how you calculate the loss or gain on exchange difference for a consolidated P&L with foreign subsidiary
5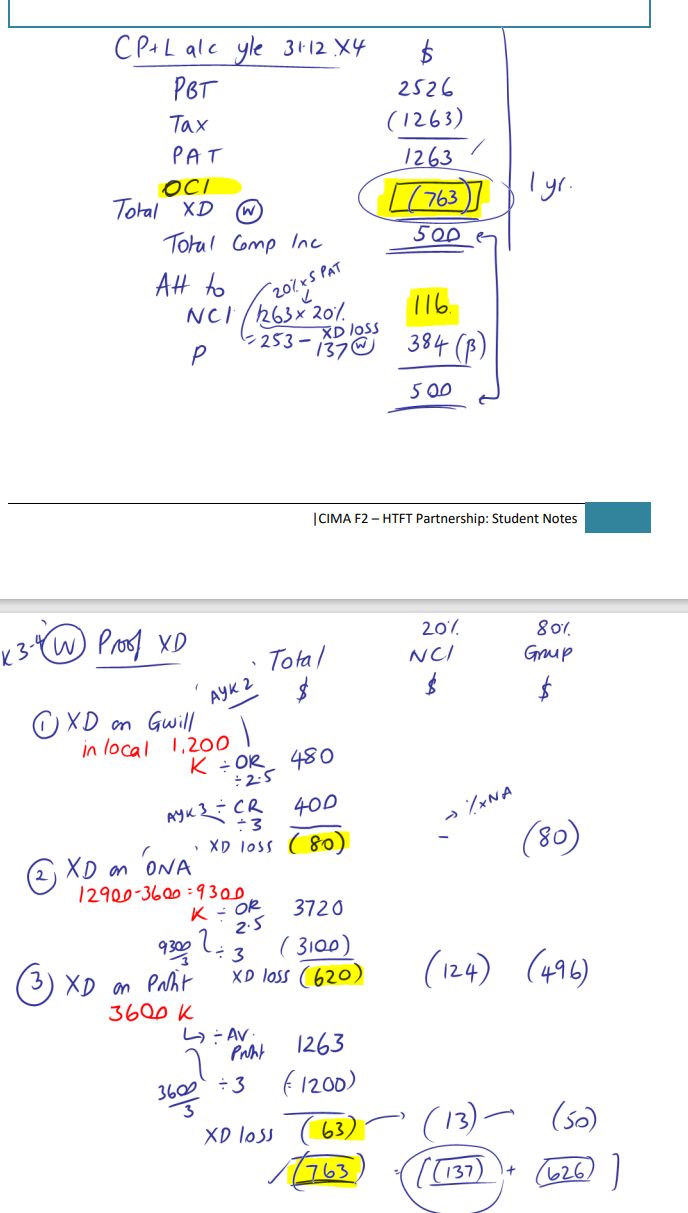
Example of consolidated P&L with foreign subsidiary
6
What is a presentational currency
The currency in which the group chooses to present its consolidated financial statements; this is a choice.
7
if an entity's does a transaction in a currency that is not their functional currency how do they record it in their individual accounts
they convert it using the spot exchange rate ie the exchange rate at the date of the transaction
8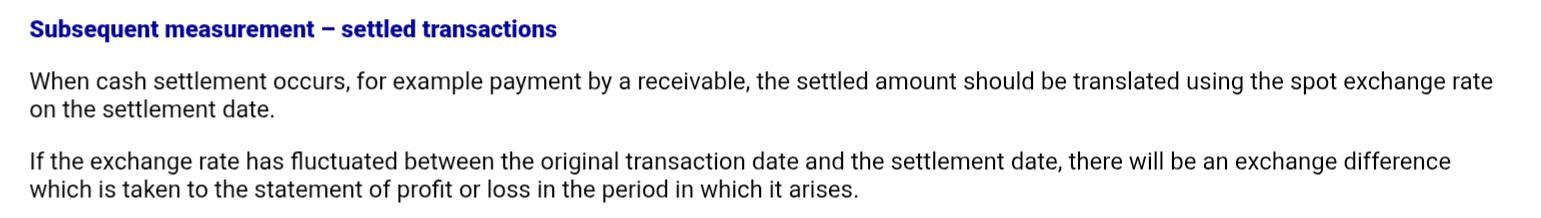
when a cash settlement occurs (ie receivables) if the exchange rate has changed since recording the transaction what happens (individual accounts)
9
in individual accounts what happens to unsettled cash items at year end (ie outstanding payables)
the balance needs to be converted to the closing rate and difference posted to p&l
10
How are individual foreign currency transactions treated under IAS 21?
Gains and losses from individual transactions (e.g., imports/exports) are recorded in the profit and loss account (P&L).
11
What is a significant factor in determining that a currency is not the functional currency?
If the majority of a company’s sales are in foreign currencies, the local currency is unlikely to be the functional currency.
12
Can a subsidiary choose its functional currency to match the parent company’s currency?
No, a subsidiary cannot choose its functional currency; it is determined by the economic environment in which it operates.
13
What is the difference between functional currency and presentational currency?
Functional currency is determined by the company’s primary economic environment, while presentational currency can be chosen for reporting purposes.
14
What rate do you use to translate assets and liabilities of a foreign subsidiary for consolidation?
Use the closing rate at the SFP (Statement of Financial Position) date.
15
What rate do you use to translate income and expenses of a foreign subsidiary for consolidation?
Use the average rate for the year
16
Where are exchange differences from foreign currency translation reflected?
In other comprehensive income for the year, and then cumulatively in reserves (either as a separate translation reserve or in retained earnings).
17
What exchange rate do you use when consolidating income and expenses
18
When consolidating a foreign subs SOFP what exchange rate should you use
19
How do you handle the cost of investment when consolidating with foreign currency translation?
Compare the cost of investment at the opening/acquisition rate to the closing rate; the difference is an exchange gain or loss added to group reserves.
20
How do you calculate group reserves (retained earnings) in the consolidated SFP?
Take the parent’s share of post-acquisition profits (in local currency), translate at the closing rate, and add any foreign exchange gain/loss on the cost of investment.
21
How to you calculate the foreign exchange gain/loss on the cost of investment
convert the investment at acquisition into your group currency using the exchange rate at acquisition. Then convert the investment amount using your closing exchange rate. The difference between the 2 is your gain or loss.
22
What is a common error when calculating goodwill in a foreign currency SFP
Using the parent’s currency investment cost instead of the subsidiary’s local currency cost.
23
What are the three components that give rise to exchange differences in consolidation? (calculating OCI on P&L)
1. Exchange difference on goodwill,
2. Exchange difference on retranslation of opening net assets,
3. Exchange difference on profit for the year.
2. Exchange difference on retranslation of opening net assets,
3. Exchange difference on profit for the year.
24
How is the exchange difference on goodwill calculated for one year? (calculating OCI on P&L)
Compare the goodwill at the opening rate (start of the year) and the closing rate (end of the year).
This means using the goodwill balance at the start of the year in the foreign currency - converting at the rate at the start of THIS year and then converting again at the closing rate to get the total exchange rate difference.
Note - same rules apply on allocating to parent and sub - if share of net assets all goes to parent, if fair value then split.
25
How do you calculate the exchange difference on opening net assets? (calculating OCI on P&L)
Retranslate the opening net assets at the opening and closing rates, and find the difference. This is opening net assets for this year
26
How is the exchange difference on profit for the year calculated? (calculating OCI on P&L)
Compare the profit translated at the average rate (P&L) and at the closing rate (SFP).
27
How are exchange differences split between the parent and NCI under the share of net assets method?
The exchange difference on goodwill goes entirely to the group (parent), while other exchange differences are split according to the NCI percentage.
If the fair value method has been use then goodwill would also be split
If the fair value method has been use then goodwill would also be split
28
What is the difference between the reserve in the SFP and the OCI in the P&L?
The reserve in the SFP is cumulative to date, while the OCI in the P&L is the movement for one year.
29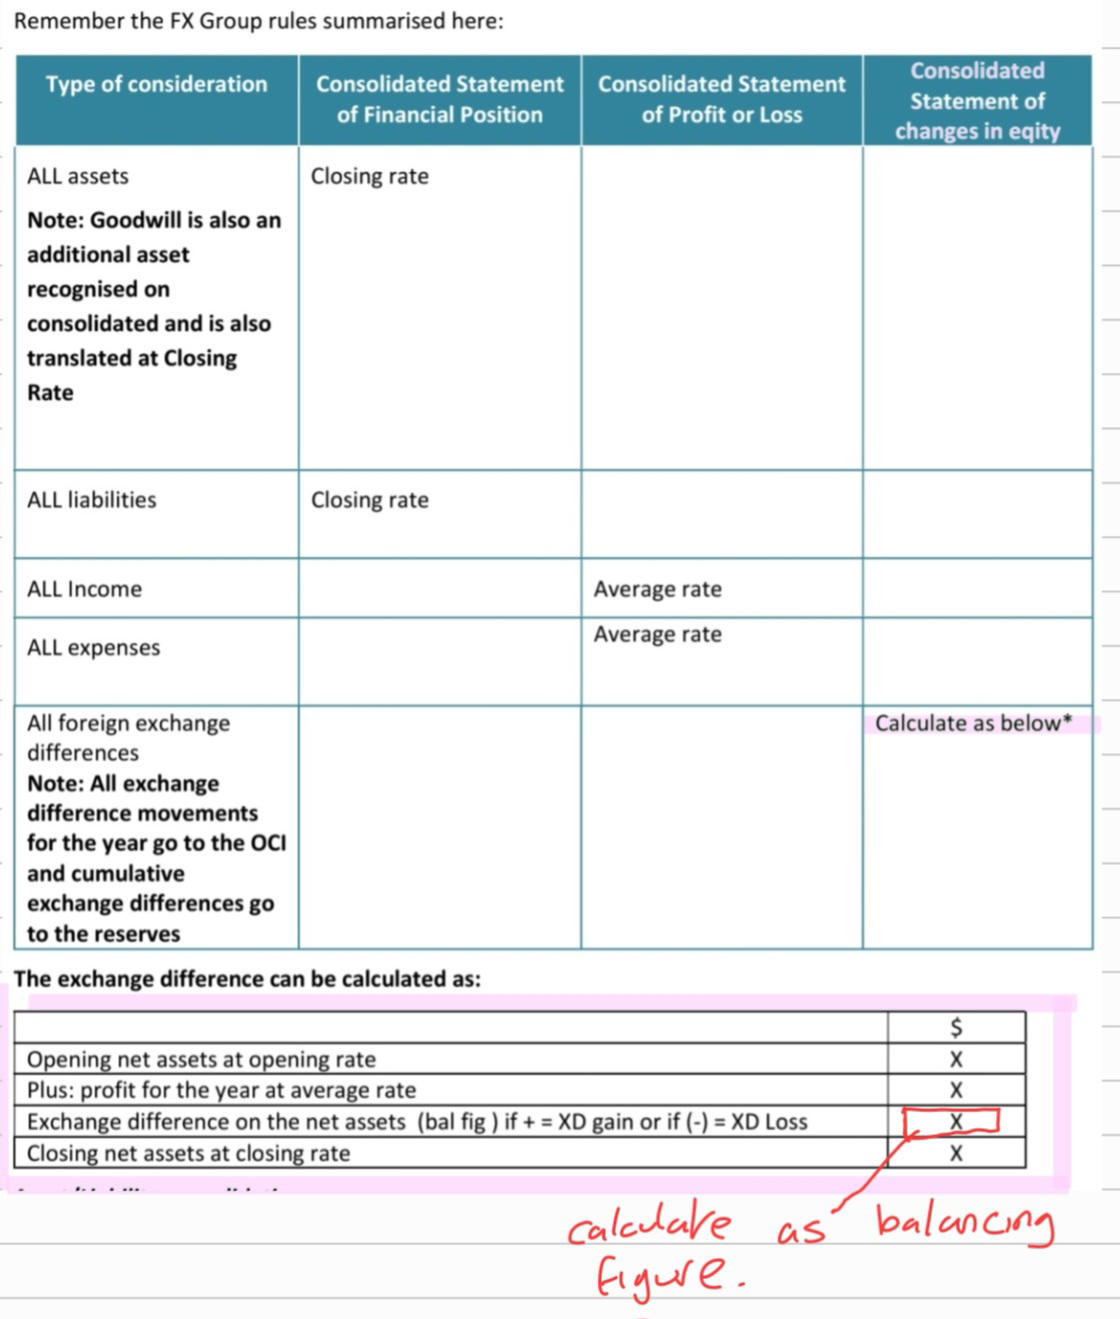
How do you calculate the total exchange rate difference on net assets
30
In foreign currencies how do you calculate Net assets of subsidiary
31
In foreign currencies how do you calculate Goodwill
32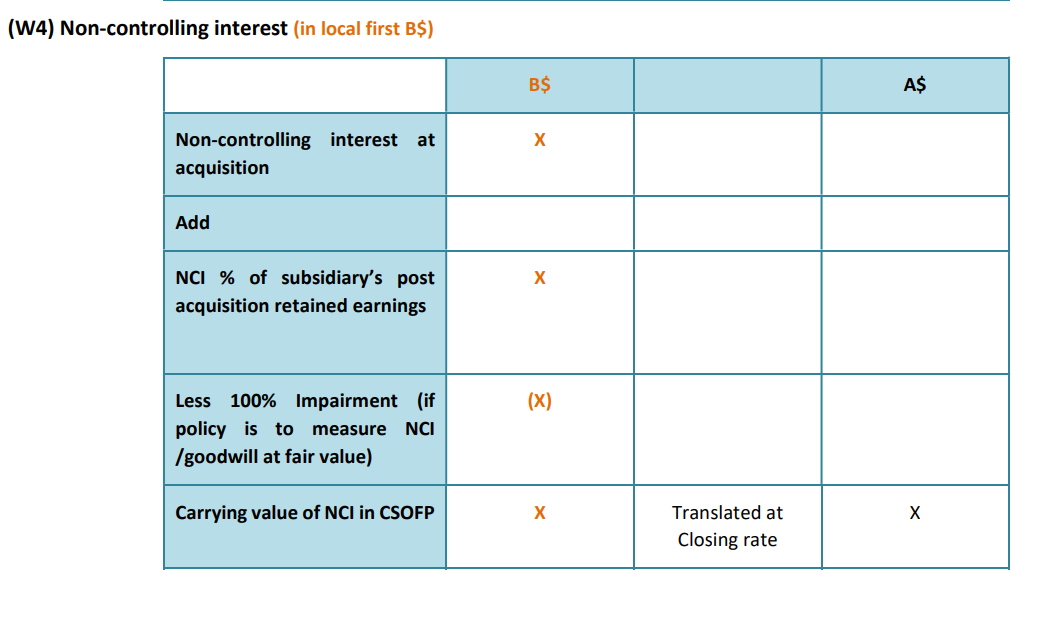
In foreign currencies how do you calculate Non controlling interest
33
In foreign currencies how do you calculate group retained earnings
34
In foreign currencies how do you calculate consolidated PPE
35
In foreign currencies how do you calculate inventories
36
In foreign currencies how do you calculate receivables
37
In foreign currencies how do you calculate consolidated cash and cash equivelents
38
In foreign currencies how do you calculate payables
39
Key examinable points
40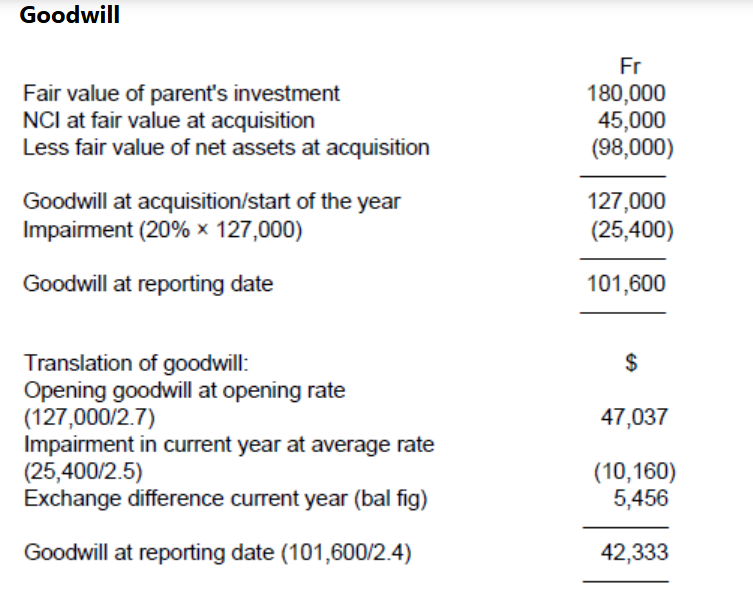
Question how how to calculate exchange gain/loss on goodwill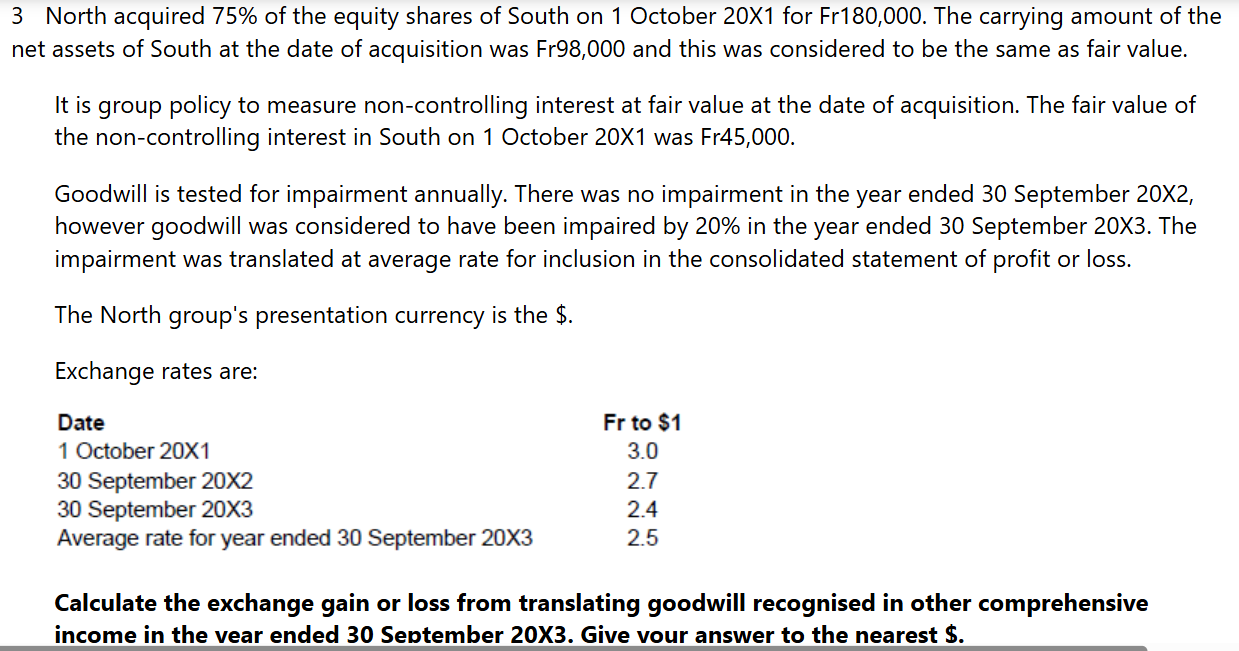
41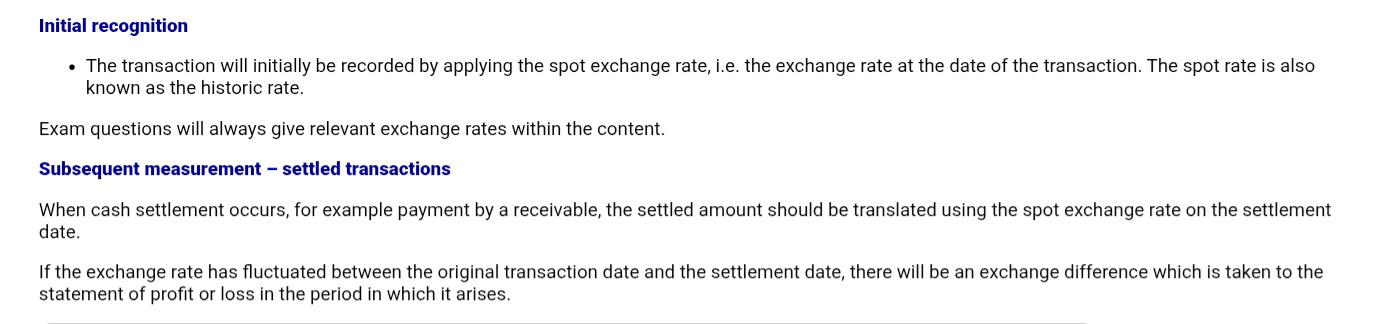
If an entity has a transaction in foreign currency how is it measured (not a subsidiary)
42
if an has non monetary items in the sofp at year end that were purchased in a foriegn currency how is it adjusted
it isn't, non monetary items are left at the spot rate
43
what are non monetary items
non current assets
inventory
investments
inventory
investments