F2 Leases
Study these flashcardsFree · spaced repetition · iPhone, Android, Mac & web
All cards
1
What three elements are important for identifying a lease under IFRS 16?
The right to control
an identified asset
and a period of time.
an identified asset
and a period of time.
2
How is "right to control" defined in the context of a lease?
The customer must have the right to obtain substantially all economic benefits from the asset and the ability to direct its use.
3
What counts as an "identified asset"
An asset that is specified explicitly or implicitly in the contract, and can be all or part of a larger asset.
4
When does the supplier retain control over an asset?
If the supplier has substantive rights to substitute the asset throughout the period or sets restrictive conditions.
5
What must a lease specify regarding the period of use?
A fixed period of time, which could be a set number of units or length (e.g., weeks, months, years).
6
What is the basic principle regarding asset recognition in leasing for two companies?
Two companies should not both show the same asset in their accounts.
7
What should the lessor do if they transfer the risks and rewards of an asset to the lessee?
The lessor should de-recognize the asset and set up a corresponding receivable.
8
How is the lease term determined in a lease contract?
The lease term includes the initial period and any extension periods if the lessee is reasonably certain to exercise the option.
9
When should an extension period at a nominal amount be included in the lease term?
If the lessee is likely to exercise the extension option due to the low cost (peppercorn/nominal), it should be included in the lease term.
10
What are the two types of leases from the lessor’s perspective under IFRS 16?
Finance Leases and Operating Leases.
11
How does a lessor account for a finance lease?
The lessor removes the asset from the balance sheet and shows a receivable (net investment) instead.
12
How does a lessor account for an operating lease?
The lessor keeps the asset on the balance sheet and accrues rental income over the profit and loss account.
13
What is the main criterion distinguishing a finance lease from an operating lease?
Whether substantially all the risks and rewards incidental to ownership are transferred.
14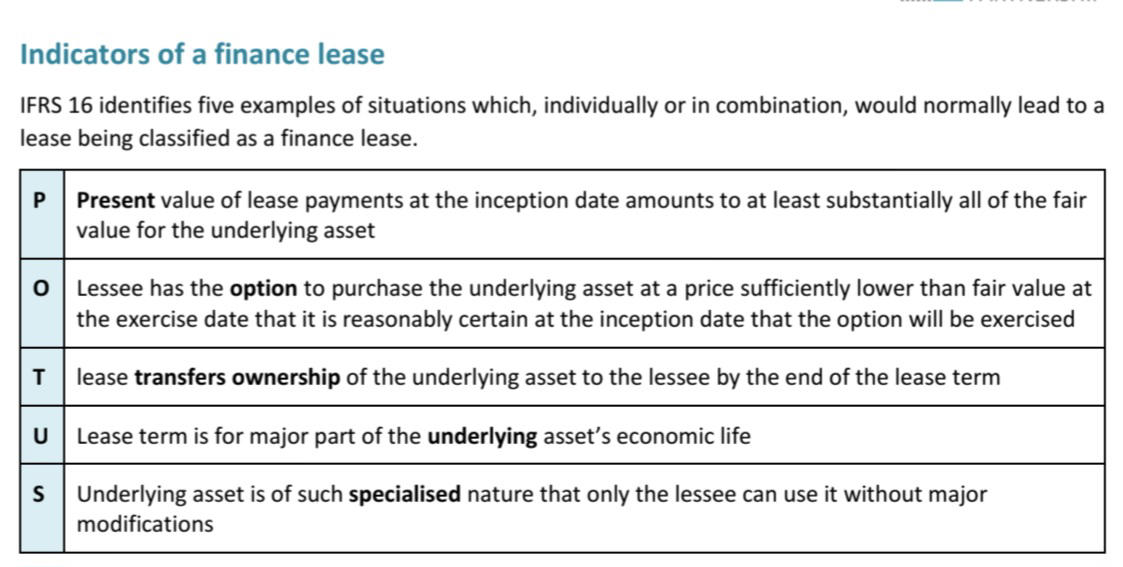
What are the indicators of a finance lease?
15
How is the net investment in the lease calculated?
It is the present value of all minimum lease payments not yet received at the commencement date, including both guaranteed and unguaranteed residual values.
16
What happens to any difference between the derecognition of the asset and recognition of the receivable?
The difference is recognized as a profit or loss in the profit and loss account.
17
Which payments should be excluded from the present value calculation for the initial net investment in the lease?
Any lease payments or deposits received on or before the commencement date (including non-refundable deposits) should be excluded.
18
What types of payments are included in the present value calculation for the initial net investment in the lease?
Fixed payments, variable payments dependent on an index or rate, guaranteed residual values, reasonably certain purchase options, and penalties for termination.
19
If an unguaranteed residual value is mentioned in a lease contract, what should you do?
Add the present value of any unguaranteed residual value to the net investment in the lease calculation.
20
What are initial direct costs in a finance lease?
Costs incurred by the lessor as a result of entering the lease, included in the initial measurement of the net investment in the lease.
21
How are initial direct costs treated in a finance lease?
They are included in the initial measurement of the net investment in the lease.
22
What is the typical journal entry for initial direct costs in a finance lease?
Debit net investment in the lease, credit cash.
23
How does treatment of initial direct costs differ between finance leases and operating leases?
Initial direct costs are included in the net investment for finance leases; the treatment is different for operating leases.
24
How is the finance charge calculated (by the lessor) if the lessee pays in advance
For example, if it is a 5 year lease term but payments in advance the discount factor used will be the 4 years. I there is a residual value amount the discount factor used will be the 5 years as it is received at the end of the lease period.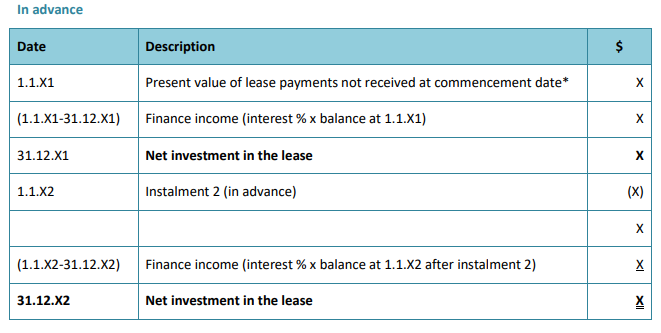
25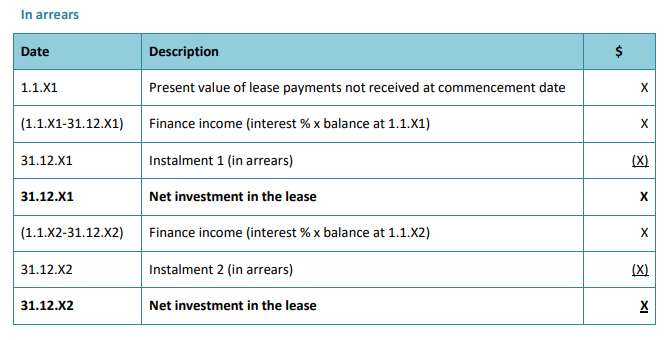
How is the finance charge calculated (by the lessor) if the lessee pays in arrears
26
How should lease payments be recognized in the P&L account for an operating lease?
Lease payments are recognized on an accruals basis, ensuring 12 months of income is reflected, typically on a straight-line or other systematic basis.
27
How should lease incentives, kickbacks, refunds, or reimbursements be treated in an operating lease?
They should be spread on a straight-line basis over the lease term
28
Where are initial direct costs added in lessor accounting for an finance lease?
They are added to the carrying value of the underlying asset.
29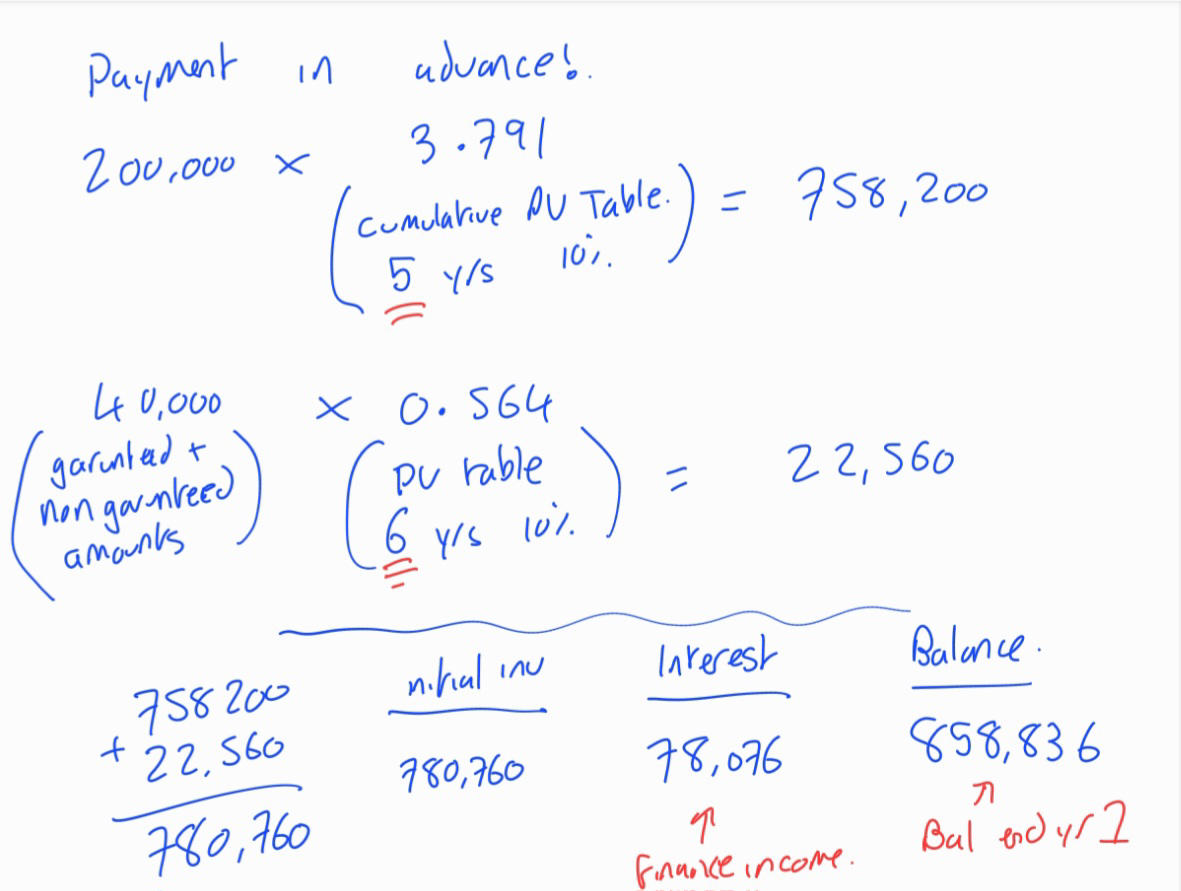
On 1 January 2018, Holly Co leases an asset to Max Co under a 6 year finance lease. Annual instalments are $200,000 payable in advance. The total estimated residual value of the asset is $40,000, of which $30,000 is guaranteed by the lessee.
The interest rate implicit in the lease is 10%.
What is the amount of the finance income that Holly Co should recognise in relation to this lease in the year end 31 December 2018?
What is the carrying value of the finance lease receivable in Holly Co as of 31 December 2018?