ACG2021 Chapter 12 (Principles of Financial Accounting)
Réviser ces flashcardsGratuit · répétition espacée · iPhone, Android, Mac et web
Toutes les cartes
1
Long-term Liabilities
Are liabilities that do not need to be paid within one year or within the entity's operation cycle, whichever is longer
2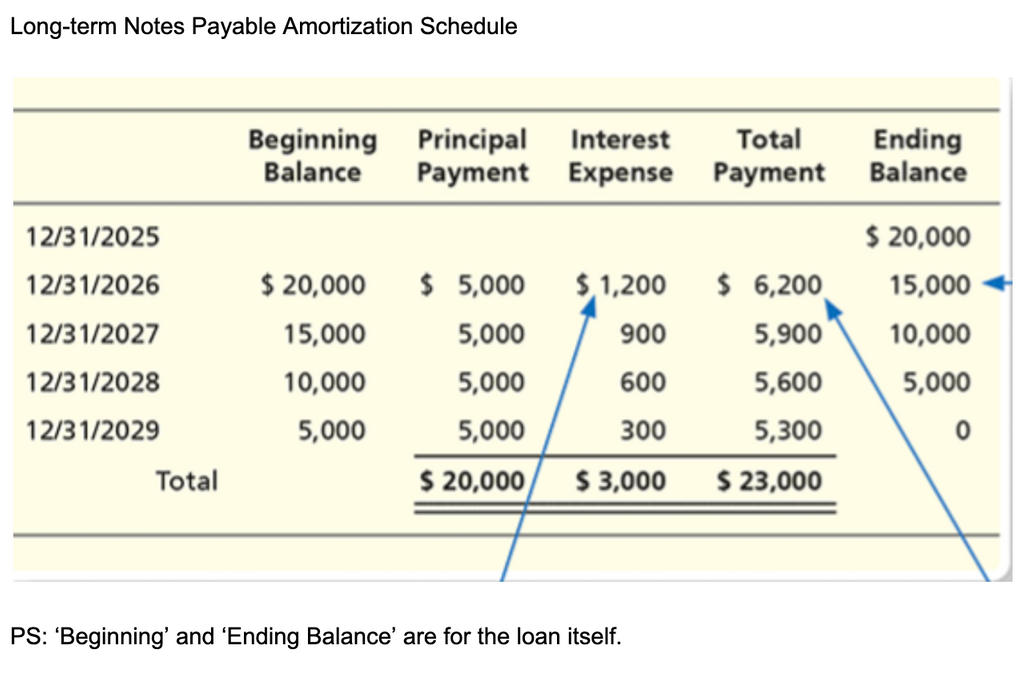
Amortization Schedule
3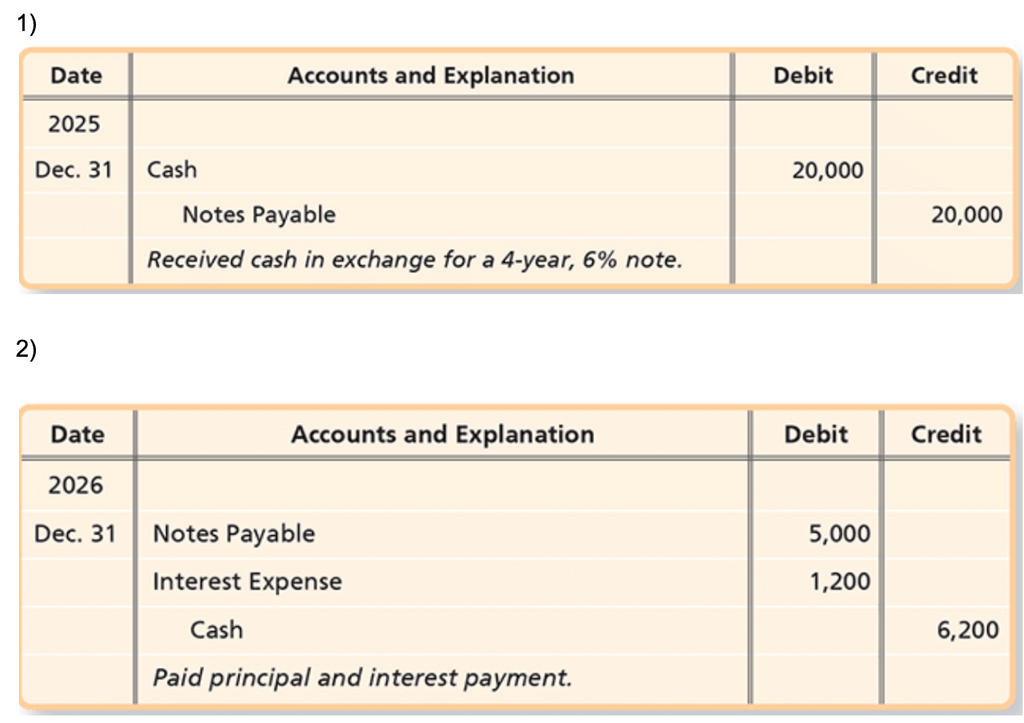
Journal Entries for
1) A company signs a \$20,000 note payable on December 31, 2025. The note will be paid over 4 years, with payments of \$5,000 plus 6% interest every December 31.
2) The company pays the first installment on December 31, 2026
1) A company signs a \$20,000 note payable on December 31, 2025. The note will be paid over 4 years, with payments of \$5,000 plus 6% interest every December 31.
2) The company pays the first installment on December 31, 2026
4
Mortgage Payable
Mortgage Payables are a type of long-term note that is secured with a specific asset. This would be the borrower's promise to transfer the legal title to a specific asset if the mortgage is not paid on schedule.
5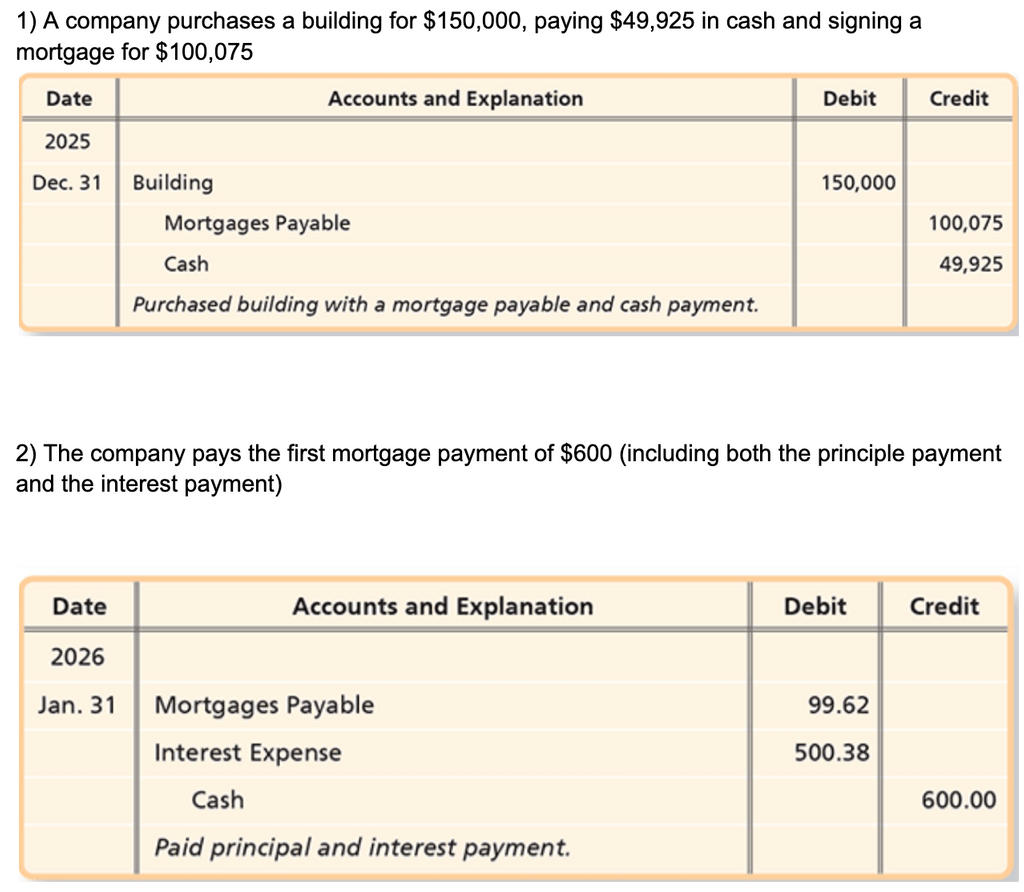
Journal Entries for Mortgage Payable
1) A company purchases a building for \$150,000, paying \$49,925 in cash and signing a mortgage for \$100,075
2) The company pays the first mortgage payment of \$600 (including both the principle payment and the interest payment)
1) A company purchases a building for \$150,000, paying \$49,925 in cash and signing a mortgage for \$100,075
2) The company pays the first mortgage payment of \$600 (including both the principle payment and the interest payment)
6
Bonds Payable
“Bonds payable are long-term debts issued to multiple lenders called bondholders, usually in increments of \$1,000 per bond. For example, a company could borrow \$100,000 from one lender (the bank), or it could issue 100 bonds payable, each at \$1,000, to 100 different lenders. “
7
Face Value
How much the company will give from a bond at the maturity date. (Usually, does not include interest)
Also called
-Maturity Value
-Par Value
-Principle
Also called
-Maturity Value
-Par Value
-Principle
8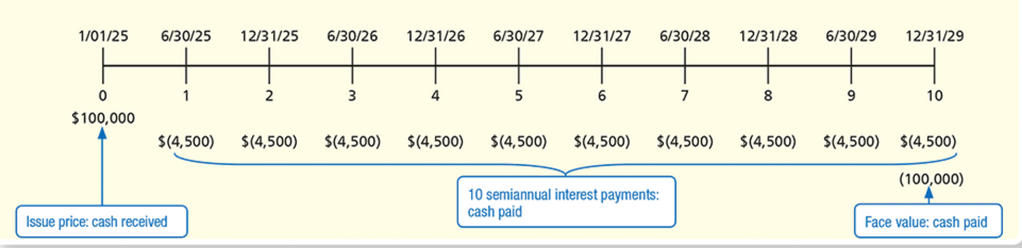
How Bond payments usually go
9
Stated Interest Rate
The interest rate that determines the amount of interest the borrower pays and the investor receives each year
Also called
-Face Rate
-Coupon Rate
-Nominal Rate
Also called
-Face Rate
-Coupon Rate
-Nominal Rate
10
Four Types of Bonds
1. Term Bonds
2. Serial Bonds
3. Secured Bonds
4. Debentures
1. Term Bonds
2. Serial Bonds
3. Secured Bonds
4. Debentures
1. Term Bonds: Bonds that mature at a specific time. For example, \$100,000 of term bonds may all mature five years from today.
2. Serial Bonds: Such bonds mature in installments at regular intervals. For example, you get a 20,000 face-value bond, that gives 5,000 of that every year.
3. Secured Bonds: These bonds give the bondholder the right to take specified assets of the issuer if the issuer fails to pay principal or interest.
4. Debentures: Such bonds are unsecured bonds that are not backed by assets. They are backed only by the creditworthiness of the bond issuer.
2. Serial Bonds: Such bonds mature in installments at regular intervals. For example, you get a 20,000 face-value bond, that gives 5,000 of that every year.
3. Secured Bonds: These bonds give the bondholder the right to take specified assets of the issuer if the issuer fails to pay principal or interest.
4. Debentures: Such bonds are unsecured bonds that are not backed by assets. They are backed only by the creditworthiness of the bond issuer.
11
Discount on Bonds Payable
Premium on Bonds Payable
Premium on Bonds Payable
Discount on Bonds Payable: When the issue price is LESS than the face-value
Premium on Bonds Payable: When the issue price is MORE than the face-value
Premium on Bonds Payable: When the issue price is MORE than the face-value
12
Time Value of Money
Recognition that money earns interest over time
13
Present Value
This is the present value of a bond, also known as the bond's market price.
14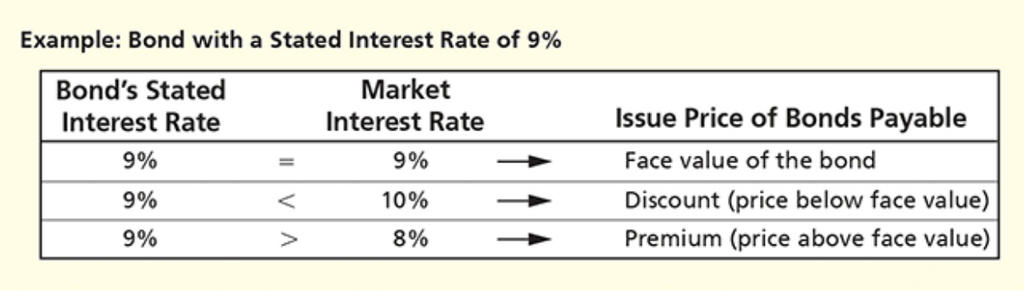
How does the bond's interest rates, relative to the market's interest rates affect the bond issue price.
15
Financial Leverage
You’re making more from the borrowed money than it costs to borrow it.
16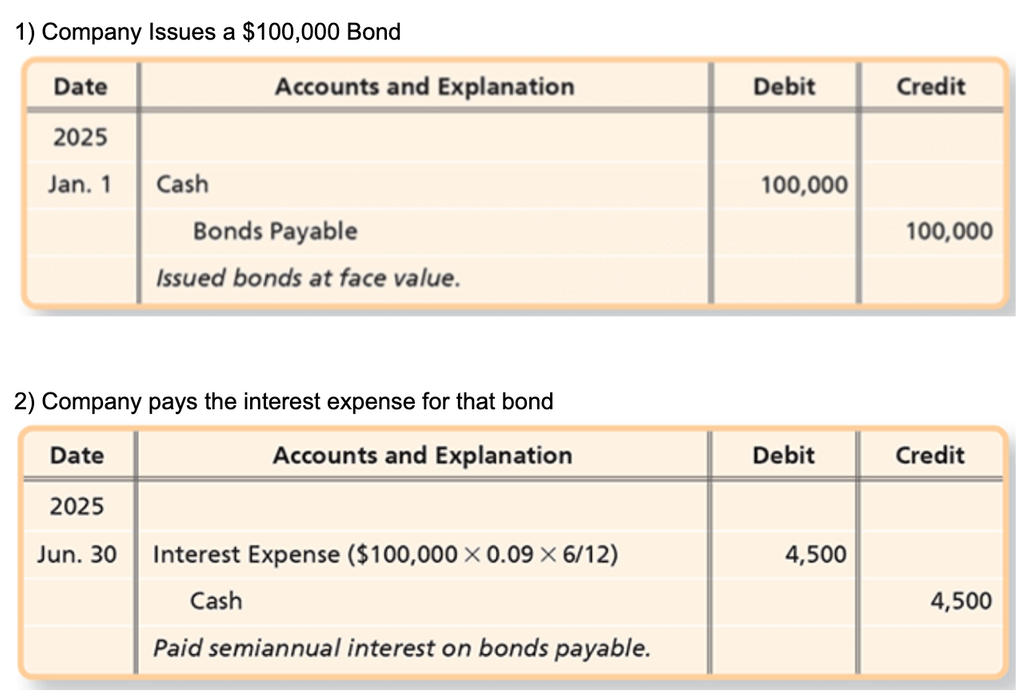
Issuing Bonds At Face Value
1) Company Issues a \$100,000 Bond
2) Company pays the interest expense for that bond
1) Company Issues a \$100,000 Bond
2) Company pays the interest expense for that bond
17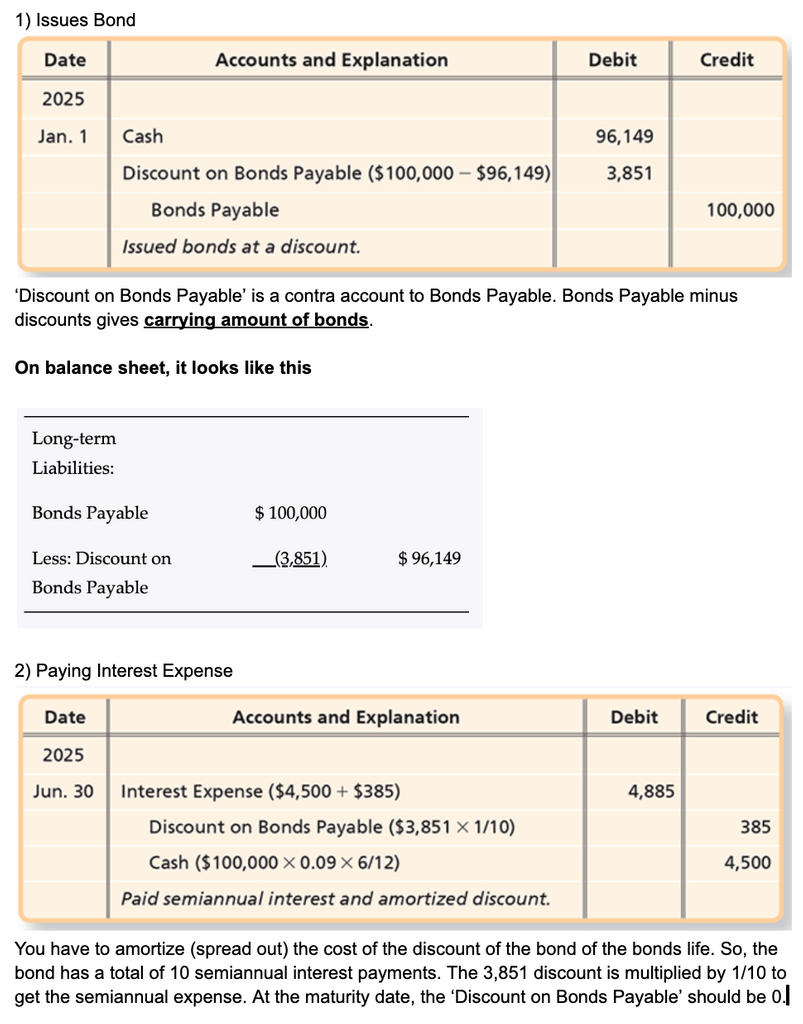
Issuing Bonds At Discount (Below Face-Value)
1) Suppose a company issues a bond at a face-value of \$100,000 bond at 9%, when the market rate for bonds is 10%. This then makes the bond market price worth \$96,149, which is \$3,851 lower than the face-value.
2) The company pays the interest expense for the bond.
1) Suppose a company issues a bond at a face-value of \$100,000 bond at 9%, when the market rate for bonds is 10%. This then makes the bond market price worth \$96,149, which is \$3,851 lower than the face-value.
2) The company pays the interest expense for the bond.
18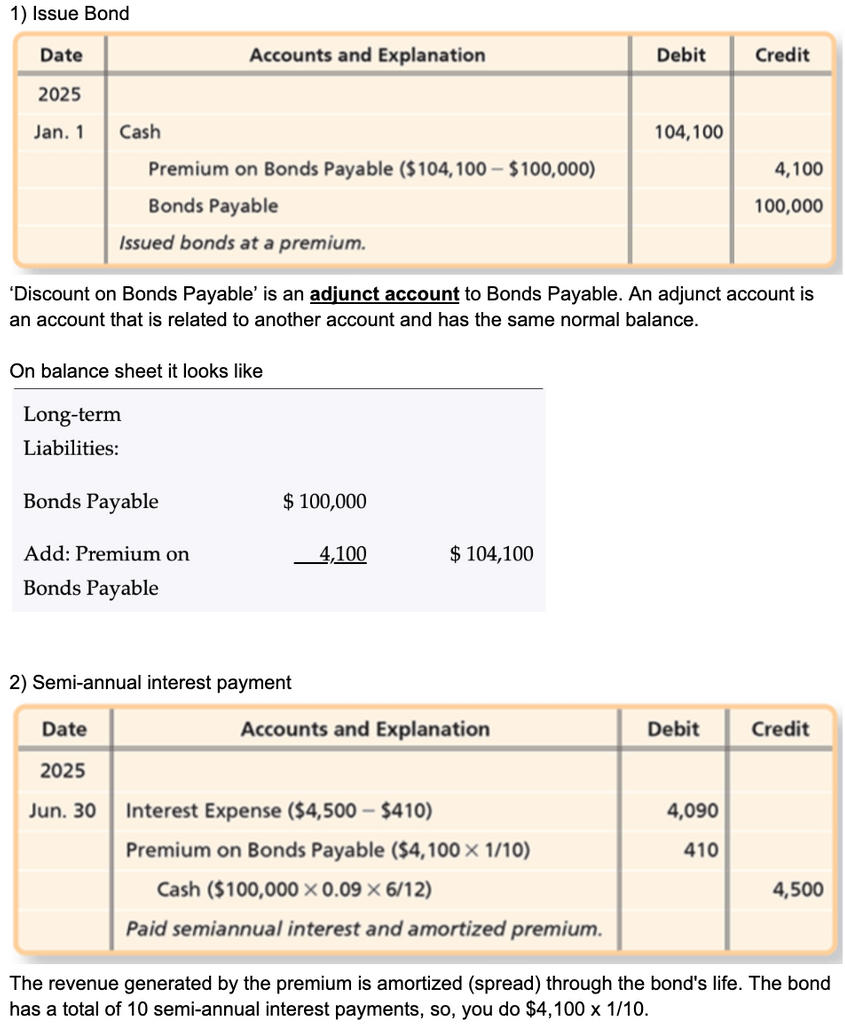
Issuing Bonds At Premium (Above Face Value)
1) Suppose a company issues a bond at a face-value of \$100,000 at 9%, when the market rate for bonds is 8%. This makes the bond market price worth \$104,100, which is 4,100 higher than the face value.
2) The company pays the interest expense for the bond.
1) Suppose a company issues a bond at a face-value of \$100,000 at 9%, when the market rate for bonds is 8%. This makes the bond market price worth \$104,100, which is 4,100 higher than the face value.
2) The company pays the interest expense for the bond.
19
Bond Retirement vs Bond Default
Bond retirement is when the borrower has enough to pay you back fully, before the maturity date, and does so.
Bond Default is when the borrower doesn't have the money to pay.
Bond Default is when the borrower doesn't have the money to pay.
20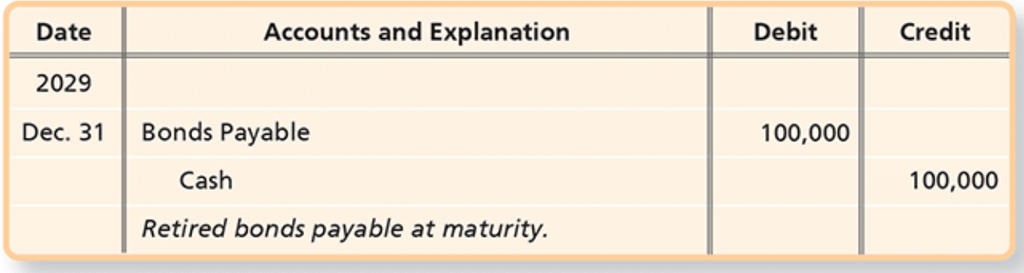
Journal Entry for
A company who issued a bond, decided that they are going to retire the bond and give all the money back.
A company who issued a bond, decided that they are going to retire the bond and give all the money back.
21
Callable Bonds
Bonds where the issuer can call (pay off) the bond for a specific price whenever they like
(The specific price is usually slightly higher than the face-value)
(The specific price is usually slightly higher than the face-value)
22
1) How to retire a bond?
2)How to determine if it's a gain or loss?
3) What the journal Entry
2)How to determine if it's a gain or loss?
3) What the journal Entry
1)
1. Record partial-period amortization of discount or premium and partial-period interest payment if the retirement date does not fall on an interest payment date.
2. Remove the portion of unamortized Discount or Premium that relates to the bonds being retired.
3. Debit Bonds Payable at face value.
4. Credit a gain or debit a loss on retirement.
5. Credit Cash for amount paid to retire the bonds
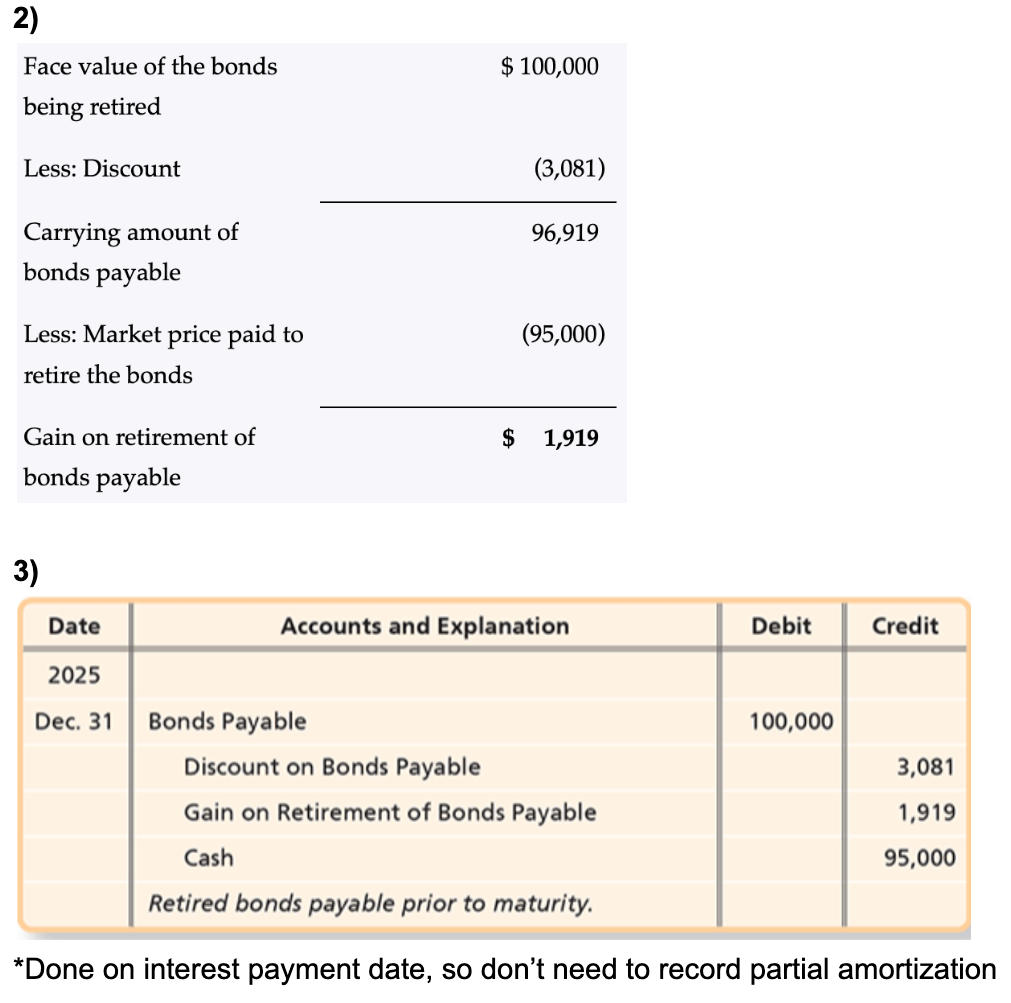
1. Record partial-period amortization of discount or premium and partial-period interest payment if the retirement date does not fall on an interest payment date.
2. Remove the portion of unamortized Discount or Premium that relates to the bonds being retired.
3. Debit Bonds Payable at face value.
4. Credit a gain or debit a loss on retirement.
5. Credit Cash for amount paid to retire the bonds
23
Debt to equity ratio
Total liabilities / Total Equity
This ratio measures financial leverage. The higher the debt to equity ratio, the greater financial risk.
This ratio measures financial leverage. The higher the debt to equity ratio, the greater financial risk.
24
Annuity
A stream of equal cash payments made at equal time intervals.
25
Present Value of a Bond
How much money would you pay now, for the bond, to receieve X amount in the future.
For example,
you wouldn't pay \$100, to get \$100 in a year. But, you would pay \$75 to get \$100 in return in a year.
For example,
you wouldn't pay \$100, to get \$100 in a year. But, you would pay \$75 to get \$100 in return in a year.
26
Future Value of a Bond
How much money in total would be received, including ALL interest payments.
27
What does 0.990 signify?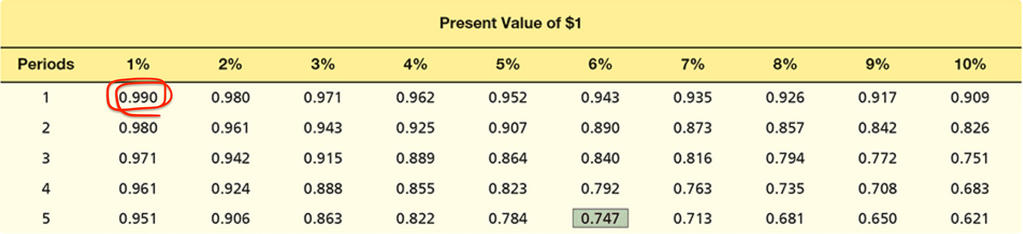
What is the value today of receiving \$1 from a bond in 1 year, if the required interest rate is 1%?
28
You need to know how much a bond is worth today. The bond pays \$100 per year for 5 years, then \$1,000 at year 5.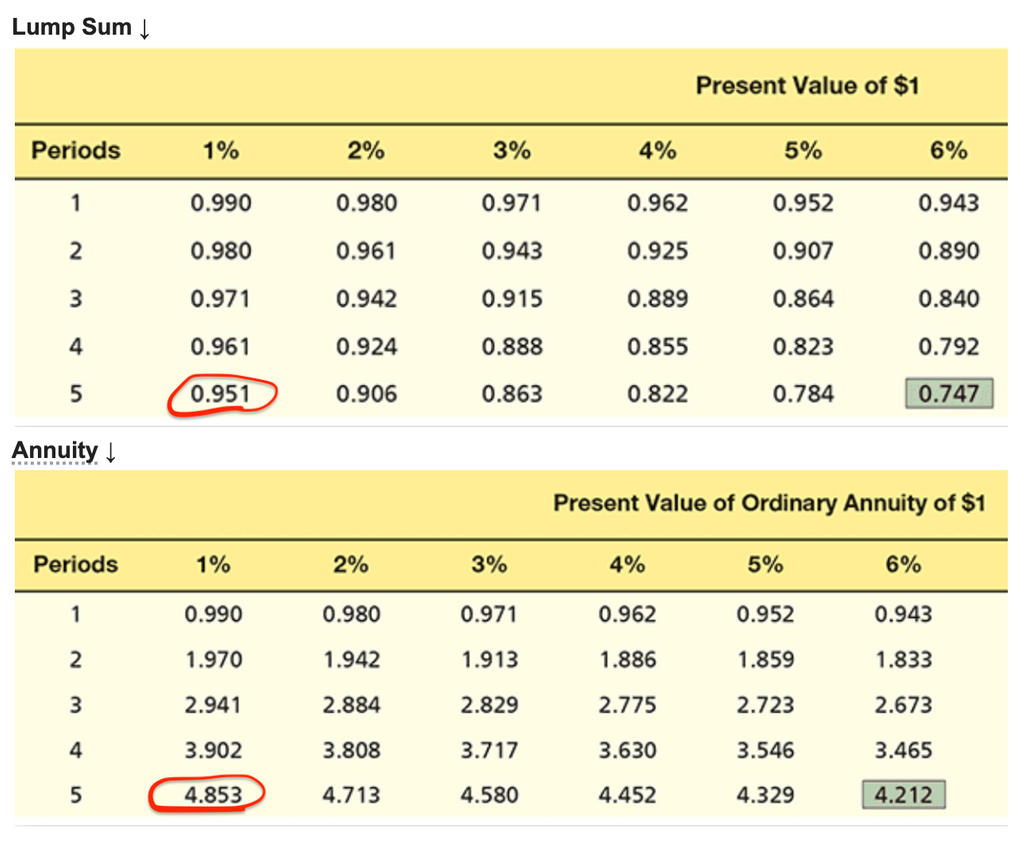
Step 1:
Use PV Factor Table
-Since interest rate is 1% and the period is 5 years, the PV factor is 0.951 for lump-sum.
-Since interest rate is 1% and the period is 5 years, the PV factor is 4.853 for annuity.
(They came from DIFFERENT TABLES!!!!!!!)
Step 2:
Lump-sum: 1,000 x 0.951 = 951
Annuity: 100 x 4.852 = 485.3
(Do NOT need to multiply annuity by 5, since the PV factor takes that into account)
Step 3:
Lump-Sum + Annuity = Bond Present Value
951 + 485.3 = 1436.3
Use PV Factor Table
-Since interest rate is 1% and the period is 5 years, the PV factor is 0.951 for lump-sum.
-Since interest rate is 1% and the period is 5 years, the PV factor is 4.853 for annuity.
(They came from DIFFERENT TABLES!!!!!!!)
Step 2:
Lump-sum: 1,000 x 0.951 = 951
Annuity: 100 x 4.852 = 485.3
(Do NOT need to multiply annuity by 5, since the PV factor takes that into account)
Step 3:
Lump-Sum + Annuity = Bond Present Value
951 + 485.3 = 1436.3
29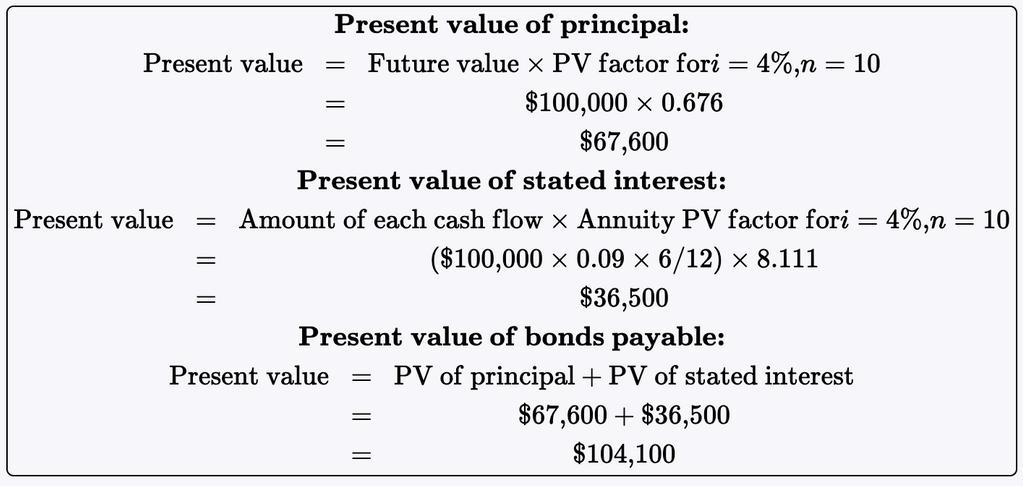
1) Equation for Present Value of Principle (Lump-sum)
2) Equation for Present Value of Interest (Annunity)
3) Equation for Present Value of Bond Payable
2) Equation for Present Value of Interest (Annunity)
3) Equation for Present Value of Bond Payable
30
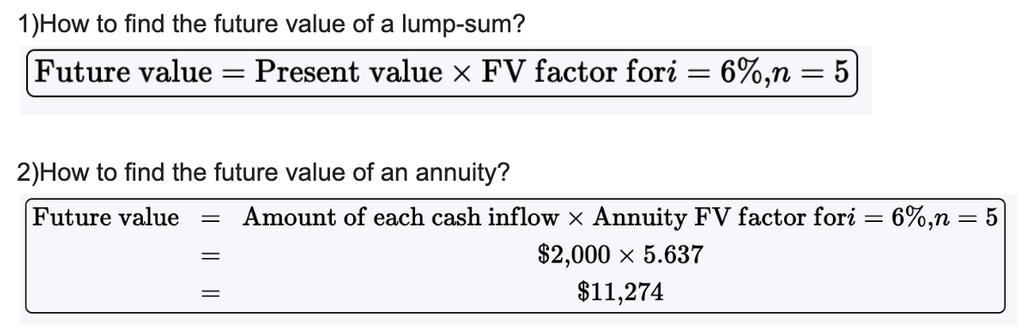
1)How to find the future value of a lump-sum?
2)How to find the future value of an annuity?
2)How to find the future value of an annuity?
Quick Answer: The same as finding the present value. Just look at the specific table and find the PV (in this case FV) factor based on the interest and periods, and then just multiply it.
31
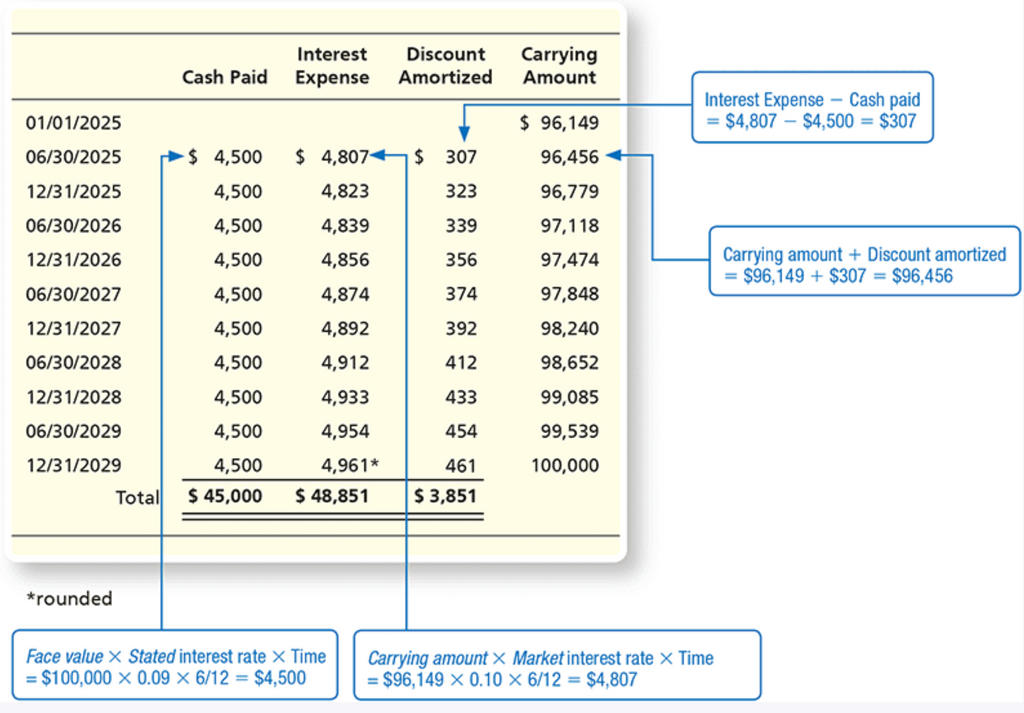
Effective-interest Amortization Method
*This method is GAAP
IMPORTANT!
Cash Paid: Face Value x Stated Interest x Time
Interest Expensed: Face Value x Market Interest x Time
Discounted Amortized: Interest Expense - Cash Paid
EVEN MORE IMPORTANT
If Interest Expense > Cash Paid
-You have a discount
-Carrying Value increases
If Cash paid > Interest Expense
-You have a premium
-Carrying Value decreases
IMPORTANT!
Cash Paid: Face Value x Stated Interest x Time
Interest Expensed: Face Value x Market Interest x Time
Discounted Amortized: Interest Expense - Cash Paid
EVEN MORE IMPORTANT
If Interest Expense > Cash Paid
-You have a discount
-Carrying Value increases
If Cash paid > Interest Expense
-You have a premium
-Carrying Value decreases
32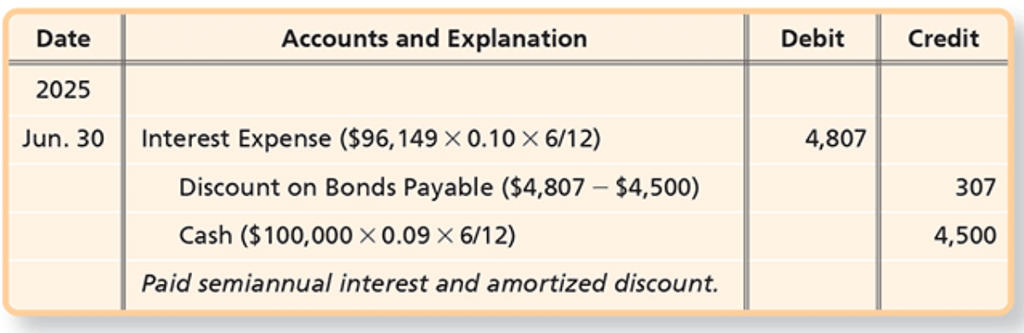
In the Effective-interest Amortization Method method, how would you journalize the expense? (If its a discount bond)
33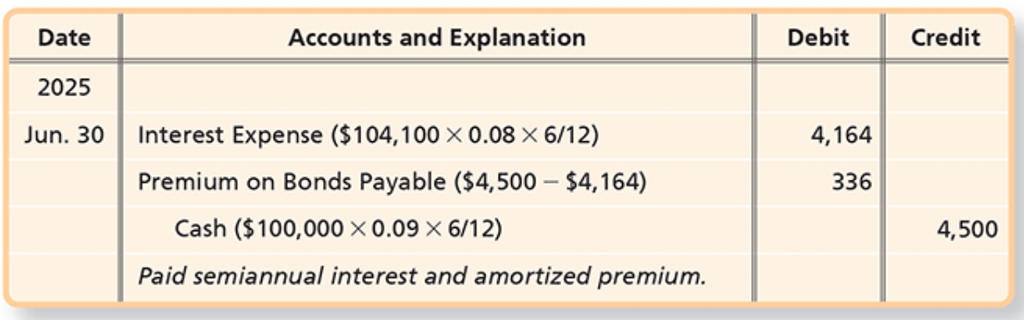
In the Effective-interest Amortization Method method, how would you journalize the expense? (If its a Premium Bond)
Plus de flashcards : Économie et gestion
Consolidated Statement of Financial Position (SOFP)Économie et gestion · AnglaisEllaHealthcare Information: HMIS and Data ComplianceÉconomie et gestion · AnglaisnightmareSupply Chain Management Exam 2Économie et gestion · AnglaisMILESSON 1: INTRODUCTION TO I.T. IN BUSINESSÉconomie et gestion · AnglaisDionCommercial Banking Ch 9Économie et gestion · AnglaisjoaoplsouzaChapter 10 Vocab - Marketing ManagementÉconomie et gestion · Anglaisbevo612MIS Final ReviewÉconomie et gestion · AnglaisLexieChapter 15 Vocab - Marketing ManagementÉconomie et gestion · Anglaisbevo612TCP T1 NotesÉconomie et gestion · AnglaiswowiepowProfitabiltyÉconomie et gestion · AnglaisDigbyChapter 13 Vocab - Supply ChainÉconomie et gestion · Anglaisbevo612P2 Treatment of Uncertainty & Risk in decision makingÉconomie et gestion · AnglaisElla
Tous les decks : Économie et gestion
Révise ces decks dans l’app
Gratuit sur iPhone, Android, Mac et le web. Ajoute n’importe quel deck à ton compte en un tap.

