ACG2021 Chapter 8 (Principles of Financial Accounting)
Diese Karteikarten lernenKostenlos · Spaced Repetition · iPhone, Android, Mac & Web
Alle Karten
1
Receivable (Also, what are the two parties)
When a business sells a good or service to another party, and that party pays on credit.
1. Creditor: The one who receives a receivable (asset)
2. Debtor: The one who takes on the liability / payable
1. Creditor: The one who receives a receivable (asset)
2. Debtor: The one who takes on the liability / payable
2
What are the 3 types of receivables?
1. Accounts Receivable (also called trade receivables)-Represent the right that you will receive cash from a customer for goods/services you have sold them. Accounts receivables are usually collected in a short period of time (such as 30 - 60 days) and therefore are reported as a current asset.
2. Notes Receivable (also called promissory Notes)-Typically have longer terms than accounts receivables-they represent that a customer will pay the principle + interest by a certain date into the future, called the Maturity Date.
3. Other Receivable-Any other type of receivable, where there is a right to receive cash in the future. -Common ones in this category include dividend receivables, interest receivables, and tax receivables.
2. Notes Receivable (also called promissory Notes)-Typically have longer terms than accounts receivables-they represent that a customer will pay the principle + interest by a certain date into the future, called the Maturity Date.
3. Other Receivable-Any other type of receivable, where there is a right to receive cash in the future. -Common ones in this category include dividend receivables, interest receivables, and tax receivables.
3
Maturity Date
The date at which the Note is due.
4
Why should the credit department have no access to cash?
Let's say customers buy something on credit, and then send the money.
Well, the credit department could just take the cash and then mark the customer's account as “uncollectable” (meaning the company believes the customer will not pay the money they owe)
ex)A customer sends the company a check, and they just endorse it to themselves and then write them as “uncollectable”
Well, the credit department could just take the cash and then mark the customer's account as “uncollectable” (meaning the company believes the customer will not pay the money they owe)
ex)A customer sends the company a check, and they just endorse it to themselves and then write them as “uncollectable”
5
Subsidiary Ledger
Contains more details of a general ledger
*The accounts used in the journal btw are always the accounts used in the general ledger, NOT the subsidiary ledger.
*The accounts used in the journal btw are always the accounts used in the general ledger, NOT the subsidiary ledger.
6
Control Accounts vs Subsidiary Accounts
Control Account is the main account that shows the total for related accounts
Subsidiary accounts are subsets of a control account
ex)
Control Account: Accounts Receivable
Subsidiary Account:
-Accounts Receivable - Brown
-Accounts Receivable - Smith
Subsidiary accounts are subsets of a control account
ex)
Control Account: Accounts Receivable
Subsidiary Account:
-Accounts Receivable - Brown
-Accounts Receivable - Smith
7
When customers pay with credit cards, does the business receive money from the customer or the credit card company?
When the customer swipes the card, the business receives money from the credit card company with a fee.
So now, the customer owes money to the credit card company.
So now, the customer owes money to the credit card company.
8
Factoring & Pledging Receivables
Factoring: You sell the receivable to someone else for immediate cash. You no longer need to collect money from customers
Pledging: You use the receivable as collateral for a loan. If you can’t pay the loan, then the bank then has the receivable and needs to collect the money
Pledging: You use the receivable as collateral for a loan. If you can’t pay the loan, then the bank then has the receivable and needs to collect the money
9
Bad debt expense
Failure to collect from some customers paying with credit
10
There are two methods of accounting for uncollectible receivables and recording the related bad debts expense
1. Direct write-off Method
2. Allowance Method
2. Allowance Method
11
Direct write-off Method
-Used by small, non-public companies-A method of accounting for uncollectable receivables with bad debt expense when a customer's receivable is uncollectable.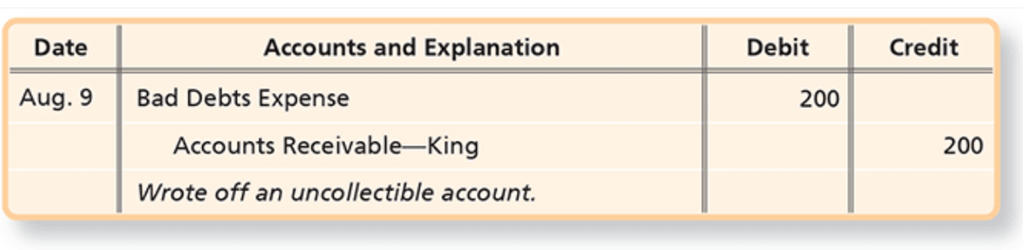
12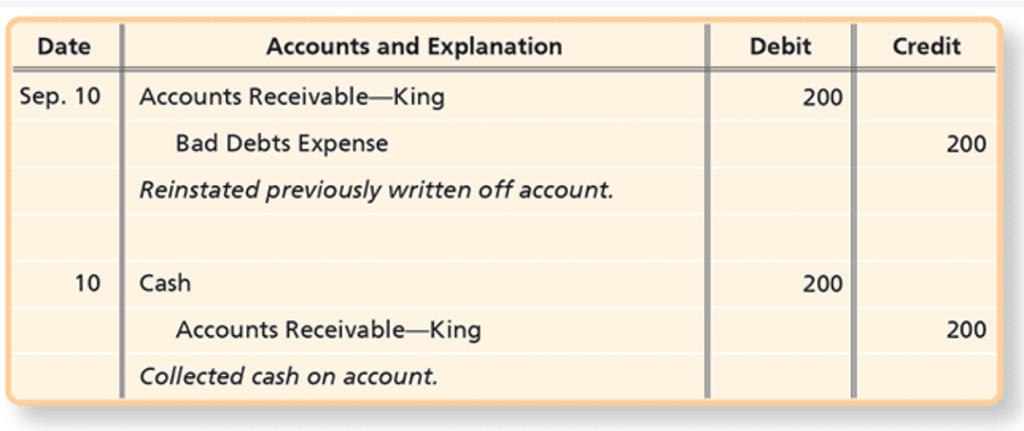
Direct write-off method (When the business already considered the receivable as uncollectable, but then the customer decides to pay)
13
Limitations of the ‘Direct write-off method’?
Does not follow the matching principle.
The matching principle is when the expenses match the revenue. The revenue of the sale was accounted for before. Then the ‘Bad Debts Expense” was accounted for after.
This is why this method is only used by small, non-public companies.
*The other method, the ‘allowance method’ is the one that follows GAAP
The matching principle is when the expenses match the revenue. The revenue of the sale was accounted for before. Then the ‘Bad Debts Expense” was accounted for after.
This is why this method is only used by small, non-public companies.
*The other method, the ‘allowance method’ is the one that follows GAAP
14
Allowance Method
-A method of accounting uncollectable receivables in which the company estimates bad debts expenses instead of waiting to see which customers the company will not collect from.
-The decrease in accounts receivables if from a contra accounts receivables account called “Allowance for Bad Debts”. A credit to this contra-account increases the account, which means more is subtracted from Account receivables.
The purpose of the “Allowance for Bad Debts” is to
1) Firstly, be used in the balance sheet to subtract to accounts receivables to show how much you expect to actually receive. You don’t want to overstate your assets. You also cannot just subtract from the receivable since it still technically exists, even if you don’t expect to make 100% of its returns.
2) Then, if the collections for the receivable is definitely not happening, then you undo the change made by the “Allowance for Bad debts” account and then just reduce Accounts receivable.
-The decrease in accounts receivables if from a contra accounts receivables account called “Allowance for Bad Debts”. A credit to this contra-account increases the account, which means more is subtracted from Account receivables.
The purpose of the “Allowance for Bad Debts” is to
1) Firstly, be used in the balance sheet to subtract to accounts receivables to show how much you expect to actually receive. You don’t want to overstate your assets. You also cannot just subtract from the receivable since it still technically exists, even if you don’t expect to make 100% of its returns.
2) Then, if the collections for the receivable is definitely not happening, then you undo the change made by the “Allowance for Bad debts” account and then just reduce Accounts receivable.
15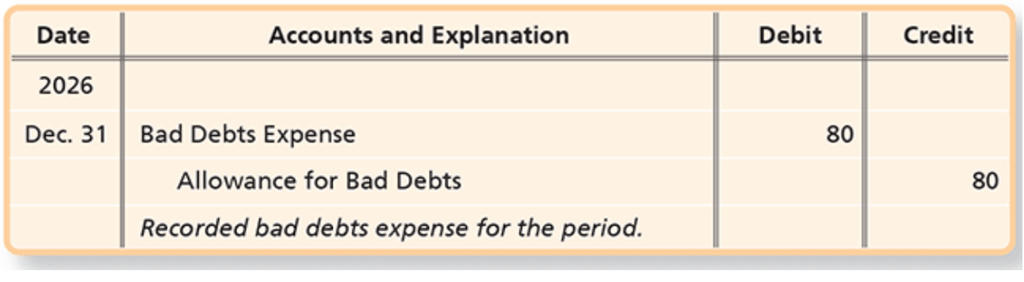
Allowance Method journal Entry for
-Lets say a company estimates that \$80 of their receivables for a period is uncollectable.
-Lets say a company estimates that \$80 of their receivables for a period is uncollectable.
16
How is Accounts receivables listed in the balance sheet in the Allowance Method
It is listed in the Net Realizable Value, which is the value the company expects to collect from accounts receivables
*The image shows how this could look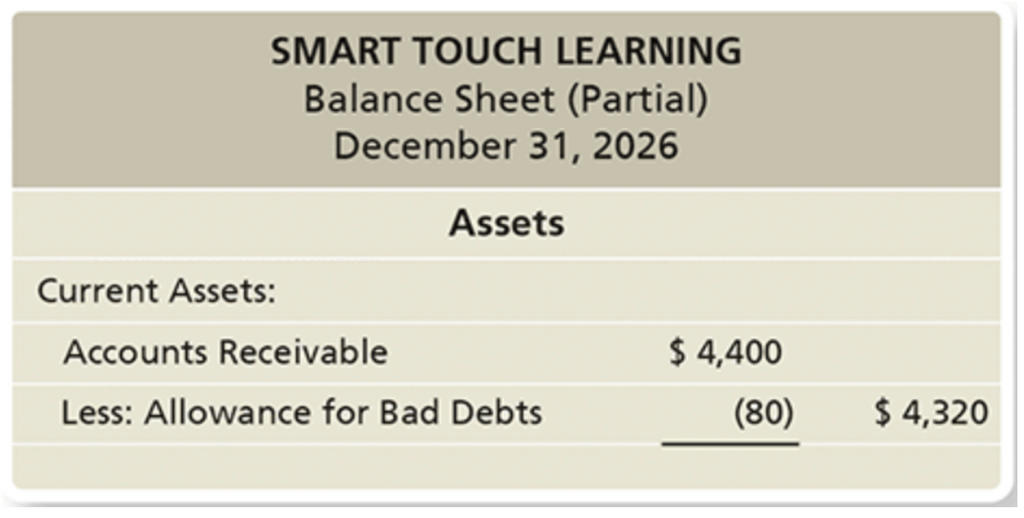
*The image shows how this could look
17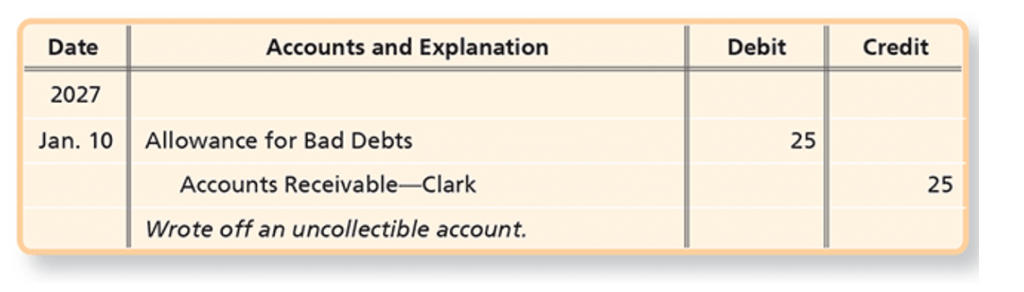
Journal Entry for when you cannot collect \$25 from a customer (Allowance Method)
18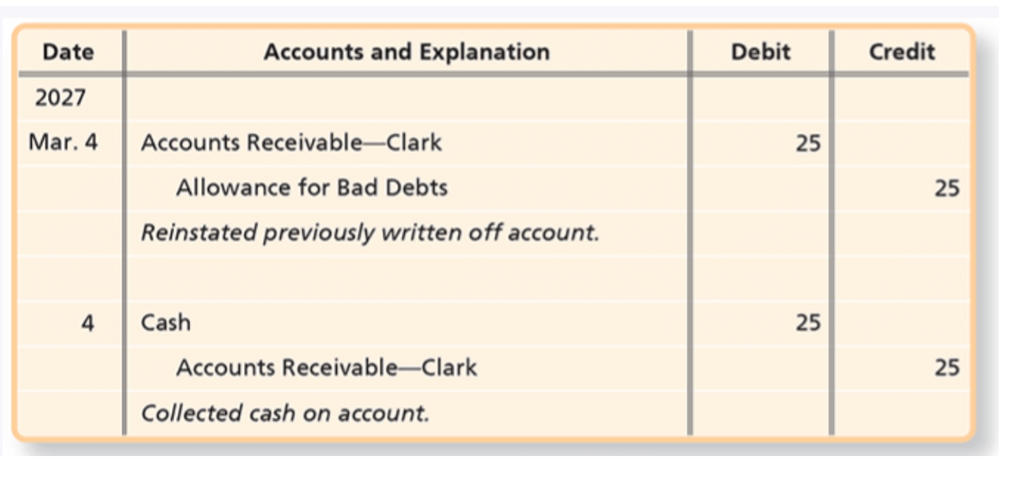
Journal Entry for when you don’t expect to receive \$25 from a customer and record it as uncollectable, but then they pay.
19
Explanation:
1) Adjustable entry explained:
-You estimate receivables that are uncollectable.
-You then have the allowance for bad debts to not overstate your accounts receivable (explanation: Account will be used in the balance sheet to subtract to accounts receivables to show how much you expect to actually receive. You don’t want to overstate your assets. You also cannot just subtract from the receivable since it still technically exists, even if you don’t expect to make 100% of its returns. )
2) write off a definite uncollectable receivable
-You undo the changes made from the “Allowance for Bad Debts”
-You then just reduce Accounts receivables
3)
-Redo the write off
-You record the cash and then the decrease in receivables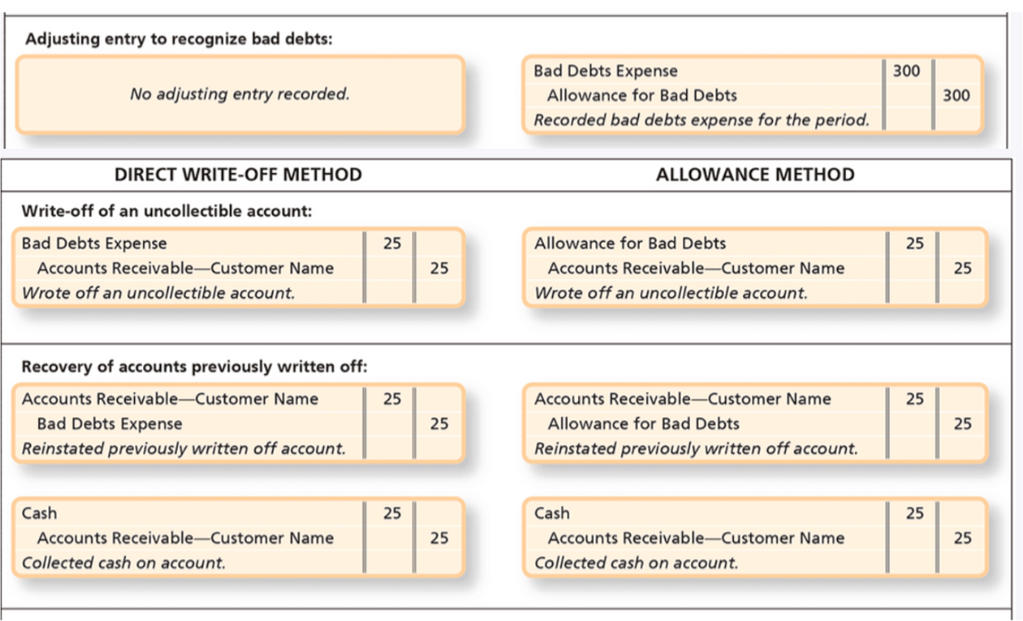
MAIN FLASH CARD! IMPORTANT
Difference in journal Entries between ‘Direct write-off method’ and ‘Allowance Method’?
Difference in journal Entries between ‘Direct write-off method’ and ‘Allowance Method’?
Explanation:
1) Adjustable entry explained:
-You estimate receivables that are uncollectable.
-You then have the allowance for bad debts to not overstate your accounts receivable (explanation: Account will be used in the balance sheet to subtract to accounts receivables to show how much you expect to actually receive. You don’t want to overstate your assets. You also cannot just subtract from the receivable since it still technically exists, even if you don’t expect to make 100% of its returns. )
2) write off a definite uncollectable receivable
-You undo the changes made from the “Allowance for Bad Debts”
-You then just reduce Accounts receivables
3)
-Redo the write off
-You record the cash and then the decrease in receivables
20
How to estimate uncollectibles? (from the allowance method)
There are three ways
1. Percent-of-sales
2. Percent-of-Receivables
3. Ageing-of-Receivables
1. Percent-of-sales
2. Percent-of-Receivables
3. Ageing-of-Receivables
21
Percent-of-sales
1. Percent-of-sales
-Find the normal percentage of sales which is uncollectable. Then multiple that percentage to the current period sales.
FROMULA: Bad Debt Expense = Credit Sales x Estimated % Uncollectible
ex)
-The percentage of sales which is uncollectable is normally 0.005%.
-The current period sales is 60,000
-60,000 x 0.005 = \$300 Which is the estimate of uncollectibles
-Find the normal percentage of sales which is uncollectable. Then multiple that percentage to the current period sales.
FROMULA: Bad Debt Expense = Credit Sales x Estimated % Uncollectible
ex)
-The percentage of sales which is uncollectable is normally 0.005%.
-The current period sales is 60,000
-60,000 x 0.005 = \$300 Which is the estimate of uncollectibles
22
Percent-of-Receivables
2. Percent-of-receivables
-Find the normal percentage of receivables which is uncollectable. Then multiple that percentage to the “unadjusted accounts receivables balance”.
FORMULA:Target Balance = Accounts Receivable × Estimated % Uncollectible
Bad Debt Expense = Target Balance - Unadjusted credit balance of Allowance of Bad Debts
or
Bad Debt Expense = Target Balance + Unadjusted debit balance of Allowance of Bad Debts
Target Balance = Total amount that should be uncollected (Which would be current month + previous months of uncollected receivables)
Credit Balance of Allowance of Bad Debts = The total amount of receivables from all previous periods that are estimately uncollected
*If you subtract Target Balance to (CR) Allowance of Bad Debts, you get the current period amount of receivables that is uncollected.
Debit Balance of Allowance of Bad Debts = the total amount of receivables from all previous periods that are written off but not previously estimated.
* Those previous write-offs need to be accounted for in this current period, so you must add it to the Bad Debt Expense to count it as an expense.
*You have to +/- allowance account since the Accounts receivable account is NOT for that current period, but for all previous periods.
-Find the normal percentage of receivables which is uncollectable. Then multiple that percentage to the “unadjusted accounts receivables balance”.
FORMULA:Target Balance = Accounts Receivable × Estimated % Uncollectible
Bad Debt Expense = Target Balance - Unadjusted credit balance of Allowance of Bad Debts
or
Bad Debt Expense = Target Balance + Unadjusted debit balance of Allowance of Bad Debts
Target Balance = Total amount that should be uncollected (Which would be current month + previous months of uncollected receivables)
Credit Balance of Allowance of Bad Debts = The total amount of receivables from all previous periods that are estimately uncollected
*If you subtract Target Balance to (CR) Allowance of Bad Debts, you get the current period amount of receivables that is uncollected.
Debit Balance of Allowance of Bad Debts = the total amount of receivables from all previous periods that are written off but not previously estimated.
* Those previous write-offs need to be accounted for in this current period, so you must add it to the Bad Debt Expense to count it as an expense.
*You have to +/- allowance account since the Accounts receivable account is NOT for that current period, but for all previous periods.
23
Ageing-of-Receivables
1. Classify receivables by age
Example categories:
0–30 days past due
31–60 days past due
61–90 days past due
Over 90 days past due
2. Assign an uncollectible percentage to each category
0–30 days → 1%
31–60 days → 5%
61–90 days → 10%
Over 90 days → 25%
3. Multiply each category balance by its % uncollectible
4. This gives the estimated bad debt for each category.
5. Add them up to get the Target balance for doubtful accounts. (PS: Target Balance = Total amount that should be uncollected )
FORMULA:
Bad Debt Expense = Target Balance - Unadjusted credit balance of Allowance of Bad Debts
or
Bad Debt Expense = Target Balance + Unadjusted debit balance of Allowance of Bad Debts
*You have to +/- current allowance since the Accounts receivable account is NOT for that current period, but for all previous periods.
Example categories:
0–30 days past due
31–60 days past due
61–90 days past due
Over 90 days past due
2. Assign an uncollectible percentage to each category
0–30 days → 1%
31–60 days → 5%
61–90 days → 10%
Over 90 days → 25%
3. Multiply each category balance by its % uncollectible
4. This gives the estimated bad debt for each category.
5. Add them up to get the Target balance for doubtful accounts. (PS: Target Balance = Total amount that should be uncollected )
FORMULA:
Bad Debt Expense = Target Balance - Unadjusted credit balance of Allowance of Bad Debts
or
Bad Debt Expense = Target Balance + Unadjusted debit balance of Allowance of Bad Debts
*You have to +/- current allowance since the Accounts receivable account is NOT for that current period, but for all previous periods.
24
Promissory Note
A written promise to pay a specified amount of money at a particular future date, usually with interest.
25
Maker of the note (debtor)
The entity that signs the note and promises to pay the required amount; the maker of the note is the debtor.
26
Payee of the note (creditor)
The entity to whom the maker promises future payment; the payee of the note is the creditor. The creditor is the company that loans the money.
27
Principal
The amount loaned
28
Interest Period
The period of time during which interest is computed. It extends from the original date of the note to the maturity date. Also called the note term.
29
Maturity Date.
As stated earlier, this is the date when final payment of the note is due. Also called the due date.
30
Maturity Value
The sum of the principal plus interest due at maturity. Maturity value is the total amount that will be paid back.
31
How to calculate Interest of a Note
Amount of Interest = Principal x Interest Rate x Time
REMEMBER:Time can be expressed as a
1) Fraction of a year in months (ex, 9/12)
2) Fraction of a year in days (ex, number of days/ 365)
REMEMBER:Time can be expressed as a
1) Fraction of a year in months (ex, 9/12)
2) Fraction of a year in days (ex, number of days/ 365)
32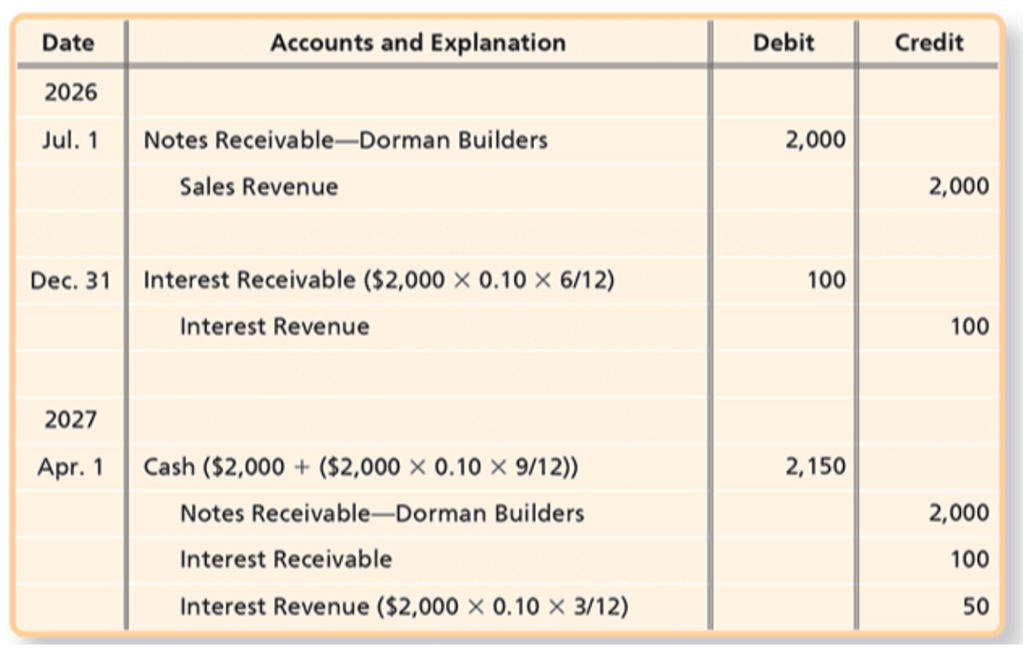
Journal Entry for a Notes Payable that starts in Jul.1 and ends in Apr. 1?
33
Journal Entry and Explanation for if a Notes Payable is defaulted (not paid)?’
The payee (guy who gave the money to be borrowed) turns the Notes Payable account into an Accounts Receivable account.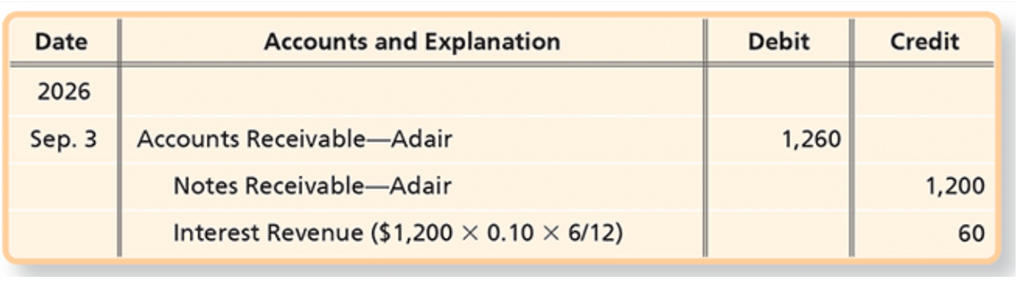
34
Another name for defaulting/not paying a loan?
Dishonoring a Note
35
Acid Test Ratio
Acid Test Ratio = (Cash including cash equivalents + Short-term investments + Net Current Receivables) / Total Current Liabilities
-Measures the companies ability to pay current assets
-A ratio higher than 1.0 is considered safe.
-Measures the companies ability to pay current assets
-A ratio higher than 1.0 is considered safe.
36
Accounts Receivable Turnover Ratio
Accounts Receivable Turnover Ratio = Net Credit Sales / Average Net Accounts Receivable
-This measures the number of times the company collects the average accounts receivable balance in a year.
-The higher the ratio, the faster they collect
-This measures the number of times the company collects the average accounts receivable balance in a year.
-The higher the ratio, the faster they collect
37
Days’ Sales in Receivables = 365 days / Accounts Receivable Turnover Ratio
-This measures how many days it takes the company to collect the average accounts receivable balance.
Days’ Sales in Receivables
Days’ Sales in Receivables = 365 days / Accounts Receivable Turnover Ratio
-This measures how many days it takes the company to collect the average accounts receivable balance.
38
When recording a sale on account, which way would it be recorded
Accounts receivables \$300
Sales Revenue. \$300
Or
Accounts receivables -Smith \$300
Sales Revenue. \$300
Accounts receivables \$300
Sales Revenue. \$300
Or
Accounts receivables -Smith \$300
Sales Revenue. \$300
“Accounts receivable -Smith”
You MUST SPECIFY the customer name.
You MUST SPECIFY the customer name.
39
Percent-of-Receivable
(New Knlowdedge)
(New Knlowdedge)
Target Balance: Accounts Receivable x % of accounts receivables thats normally uncollectedThen, minus credit balance of Allowance of Bad debts or plus debit balance of Allowance of Bad Debts.
So, target balance is the amount that should be in your allowance of Bad debts, which is estimated debits for current and previous months. You then, just minus or plus the previous Allowance of Bad debts.
So, target balance is the amount that should be in your allowance of Bad debts, which is estimated debits for current and previous months. You then, just minus or plus the previous Allowance of Bad debts.
Mehr Karteikarten: Wirtschaft
F2 intangible assetsWirtschaft · EnglischEllaCorporate planning and implementationWirtschaft · EnglischDariusE2 Managing Performance: Business StrategyWirtschaft · EnglischEllaHR: Performance ManagementWirtschaft · EnglischcolleenIntroduction to Business and Economics (Unit 1)Wirtschaft · EnglischColeInternal Controls and Business ProcessesWirtschaft · EnglischSarinaComp Exam 1Wirtschaft · EnglischLexieMGT 101Wirtschaft · EnglischKARISSA12- Securities and Investment BanksWirtschaft · EnglischMercedesF2 Long Term FinanceWirtschaft · EnglischEllaSystem Analyst and Project ManagerWirtschaft · Englisch—Griffith—Group 1 Part 1Wirtschaft · EnglischCATINOY
Lerne diese Decks in der App
Kostenlos auf iPhone, Android, Mac und im Web. Füge jedes Deck mit einem Tipp zu deinem Konto hinzu.

